NYSE close review: record S&P 500 and Nasdaq levels faced pressure from 24-year Treasury yields, higher oil, weak breadth and falling metals.
Fundamentals: Record highs in the S&P 500 and Nasdaq masked narrow participation, with only 46% of S&P 500 stocks above their 200-day averages. Multi-decade Treasury yields, elevated oil prices and inflation concerns pressured valuations and metals. Strong third-quarter earnings estimates and energy-sector gains provided support amid elevated bond volatility and hawkish Fed signals.
Technicals: Major ETF movers showed gains in Amazon, Apple and Alphabet, while Meta, IBIT and the S&P MidCap 400 ETF declined. E-mini S&P 500 and Nasdaq futures retained bullish short-, intermediate- and long-term structures near prior highs. Dow, Russell 2000 and DAX futures reflected corrective pressure, while E-mini S&P MidCap futures rebounded within a broader correction.
After Market Close daily snapshot: market news summary and sentiment, major ETFs, Magnificent 7 analysis, Indices Futures Higher Time Frame Analysis, and E-mini S&P500, Nasdaq 100, NYMEX Crude, Gold Futures Daily Chart analysis.
As of: October 7, 2026 05:00 CT
Market News Summary:
Equity-market records faced pressure from multi-decade Treasury yields, elevated oil prices, and narrow technology-led participation.
Primary Drivers & Risks:
- Primary Driver: Multi-decade Treasury yield surge
- Primary Risk: Inflation and narrow equity breadth
Tone:
Cautious, with earnings strength offset by rate and energy pressures.
Stock Market / ETFs / Indices:
The S&P 500 and Nasdaq reached all-time highs, led primarily by technology, while only 46% of S&P 500 constituents traded above their 200-day moving averages. Higher yields weighed across most sectors, compressed valuations for high-growth technology shares, and left market leadership concentrated. Third-quarter earnings estimates remained strong, with analysts citing roughly 30% year-over-year S&P 500 profit growth and Deutsche Bank projecting 34% growth.
Oil / Energy:
Crude inventories fell 3.2 million barrels versus survey expectations for a 1.7 million-barrel increase. Oil prices rose amid supply disruptions and depleted stockpile buffers, although Hormuz flows recovered to nearly 80% of pre-war levels. High oil prices supported energy ETFs and energy stocks.
Gold / Metals:
Gold tested multi-week lows near $4,066, with silver and platinum also under pressure. Rising yields coincided with the metals weakness.
Fed / Financials:
The 30-year Treasury yield returned to its highest level since 2002, while broader yields reached 24-year highs amid inflation concerns tied to oil. A strong 10-year Treasury auction and subsequent auction-related calm offered a counterpoint, but bond volatility remained elevated. Fed minutes showed unanimous backing for the September rate increase, and October rate-hike odds fell from 51% to 19% over one week.
Macro / Other:
Geopolitical tensions and wars in the Middle East and Ukraine remained linked to oil-market supply disruption concerns. Record Wall Street industry profit projections above $90 billion contrasted with stress from borrowing costs above 5% across the economy.
Conclusion:
Elevated Treasury yields, oil-market pressure, and concentrated technology leadership defined the principal index-futures backdrop. Strong earnings estimates and energy-sector support provided countervailing strength.
Inflation concerns tied to crude prices and hawkish Fed policy remained central cross-currents. Weak market breadth, declining metals, and rate-sensitive valuation pressure underscored broader equity-market strain.
Market News Sentiment
Market News Articles: 45
- Neutral: 48.89%
- Negative: 31.11%
- Positive: 20.00%
Sentiment Summary: Among 45 market news articles, sentiment was 49% neutral, 31% negative, and 20% positive, indicating neutral coverage with a negative skew.
Conclusion: Indices futures day traders are facing a news backdrop where negative articles outnumber positive articles, while neutral reporting remains dominant.
GLD,Gold Articles: 9
- Negative: 55.56%
- Neutral: 33.33%
- Positive: 11.11%
Sentiment Summary: Gold-related coverage is predominantly negative (56%), with 33% neutral and 11% positive across 9 articles.
Conclusion: The gold news tone is negative overall, indicating limited positive sentiment in this dataset.
USO,Oil Articles: 13
- Positive: 38.46%
- Neutral: 38.46%
- Negative: 23.08%
Sentiment Summary: USO and oil coverage is balanced to slightly positive, with 38% positive, 38% neutral, and 23% negative articles across 13 items.
Conclusion: Oil-related news tone is mixed, with positive and neutral coverage outweighing negative coverage.
Market Data Snapshot
ETF Snapshot of major stock market ETFs, Mag7, and others as of: October 7, 2026 05:00
Top Movers & Losers
- AMZN 259.92 Bullish 1.42% ▲
- AAPL 336.67 Bullish 0.91% ▲
- GOOG 347.37 Bullish 0.81% ▲
- IJH 72.76 Bearish -1.68% ▼
- META 721.31 Bearish -2.38% ▼
- IBIT 47.21 Bearish -2.64% ▼
Major Index ETFs: SPY, QQQ, DIA, IWM, IJH
- SPY 777.22 Bearish -0.24% ▼
- QQQ 757.73 Bearish -0.25% ▼
- DIA 511.02 Bearish -0.69% ▼
- IWM 277.70 Bearish -1.29% ▼
- IJH 72.76 Bearish -1.68% ▼
Major index ETFs were Bearish across the board: IJH led losses at -1.68%, followed by IWM at -1.29% and DIA at -0.69%. QQQ was the least negative mover at -0.25%, with SPY close behind at -0.24%, indicating comparatively contained large-cap declines versus broader small- and mid-cap weakness.
Mag 7 Stocks: AAPL, MSFT, GOOG, AMZN, META, NVDA, TSLA
- AMZN 259.92 Bullish 1.42% ▲
- AAPL 336.67 Bullish 0.91% ▲
- GOOG 347.37 Bullish 0.81% ▲
- MSFT 529.76 Bullish 0.09% ▲
- NVDA 237.47 Bearish -0.74% ▼
- TSLA 377.81 Bearish -0.75% ▼
- META 721.31 Bearish -2.38% ▼
Mixed: AMZN is the most bullish mover at +1.42%, followed by AAPL at +0.91% and GOOG at +0.81%. MSFT is marginally Bullish at +0.09%. META is the most bearish mover at -2.38%, with TSLA at -0.75% and NVDA at -0.74%.
Cross-Market ETFs: TLT, GLD, USO, IBIT
- TLT 77.14 Bearish -0.17% ▼
- USO 143.91 Bearish -0.69% ▼
- GLD 375.88 Bearish -1.67% ▼
- IBIT 47.21 Bearish -2.64% ▼
Other ETFs were Bearish across the snapshot: IBIT led losses at -2.64%, followed by GLD at -1.67% and USO at -0.69%. TLT was the least negative mover, marginally Bearish at -0.17%.
ETF, Mag7, and Cross-Market ETF Insights
Overall Tone
Mixed: broad equity ETFs and cross-market ETFs were Bearish, while select Mag7 names provided Bullish leadership.
Equity ETFs and Mag7:
Major Index ETFs were broadly Bearish, led lower by IJH at -1.68% and IWM at -1.29%, while SPY was the least negative mover at -0.24% and QQQ held near-flat at -0.25%. Mag7 performance was selective: AMZN was the most bullish mover at +1.42%, followed by AAPL at +0.91%, while META was the most bearish Mag7 name at -2.38%. DIA declined -0.69%, while NVDA and TSLA were also Bearish at -0.74% and -0.75%.
Cross-Market ETFs:
Cross-Market ETFs were uniformly Bearish, diverging from the Bullish leadership in select Mag7 names. TLT was the least negative mover at -0.17%, while IBIT was the most bearish mover at -2.64%; GLD also fell -1.67%. USO declined -0.69%, showing Bearish participation across bonds, metals, energy, and bitcoin exposure.
Futures Indices – Higher Time Frame Analysis
Summary of the current state of US Indices Futures based on higher time-frame (HTF) technical analysis as of: 2026-10-07: 17:00 CT.
US Indices Futures
- ES: YSFG/MSFG/WSFG above F0%, rising benchmarks, UTrend pivots; resistance 7897.50-7906.25, support 7752.25/7742.50.
- NQ: YSFG/MSFG/WSFG above F0%, all benchmarks rising, higher-high structure; resistance 31389.25-31660.50, pivot-reversal support 30689.00.
- YM: YSFG/MSFG above F0%, WSFG below F0%; daily/weekly DTrend, overhead 51999-52801, support 50859, reversal threshold 53247.
- EMD: YSFG/MSFG/WSFG above F0%; weekly DTrend, daily UTrend rebound; support 3600.3, resistance 3737.8, 3825.3, 3969.6.
- RTY: YSFG above F0%, MSFG neutral, WSFG below F0%; weekly DTrend, daily rebound; support 2791.5, resistance 2887.0, 2931.2.
- FDAX: MSFG/YSFG above F0%, WSFG below F0%; corrective pressure beneath benchmarks; support 24897-25001, resistance 25705, 25890-25990.
Overall State
- Short-Term: Neutral
- Intermediate-Term: Bullish
- Long-Term: Bullish
Conclusion
ES and NQ retain aligned bullish YSFG, MSFG, WSFG, benchmark, and pivot structures near prior highs. YM, RTY, and FDAX remain short-term corrective, while EMD is rebounding within a broader correction. Long-term benchmark alignment and yearly-grid positioning remain broadly bullish; near-term directional correlation is mixed between ES/NQ strength and corrective rotations in YM, RTY, and FDAX.
Note: Intra-day counter-trend pullbacks or retracements may occur, HTF is context for informational usage and market structure. Glossary: Session Fib Grids periods of YSFG:’Yearly’, MSFG:’Monthly’, WSFG:’Weekly’
For full details visit: AlphaWebTrader Technicals
ES Daily View
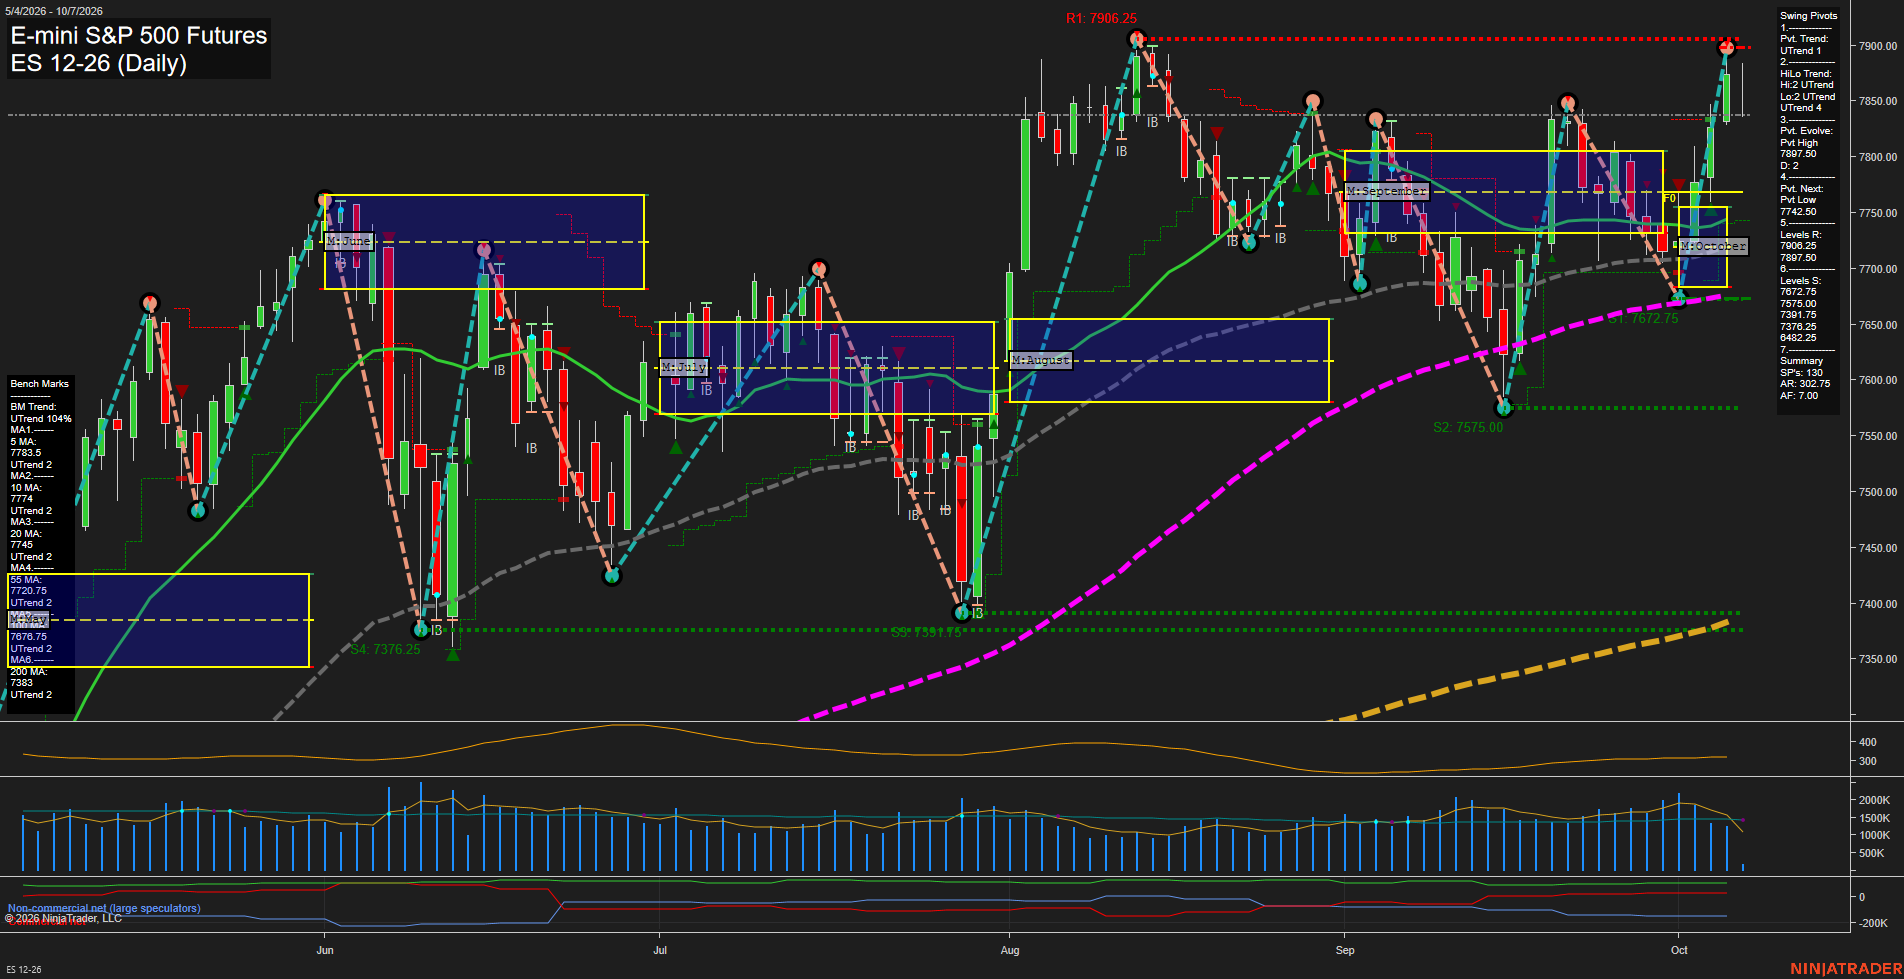
Overall Rating
- Short-Term: Bullish
- Intermediate-Term: Bullish
- Long-Term: Bullish.
Key Insights Summary
The daily structure remains broadly bullish: price is above all six rising benchmark averages, the weekly, monthly, and yearly fib-grid biases are above F0%, and both pivot trend measures remain in UTrend. The recent advance has returned price toward the 7897.50 to 7906.25 swing-resistance band after a higher-low recovery from the late-September 7575.00 area. Medium-sized bars and fast momentum show an active upside rotation, while the 319-point ATR reflects a wide daily range environment. The nearest structural downside pivot reference is 7742.50, with deeper supports at 7672.75 and 7575.00; price behavior around the 7897.50 and 7906.25 resistance cluster defines whether the rally is extending or consolidating beneath prior highs.
View charts on: AlphaWebTrader HTF Charts
NQ Daily View
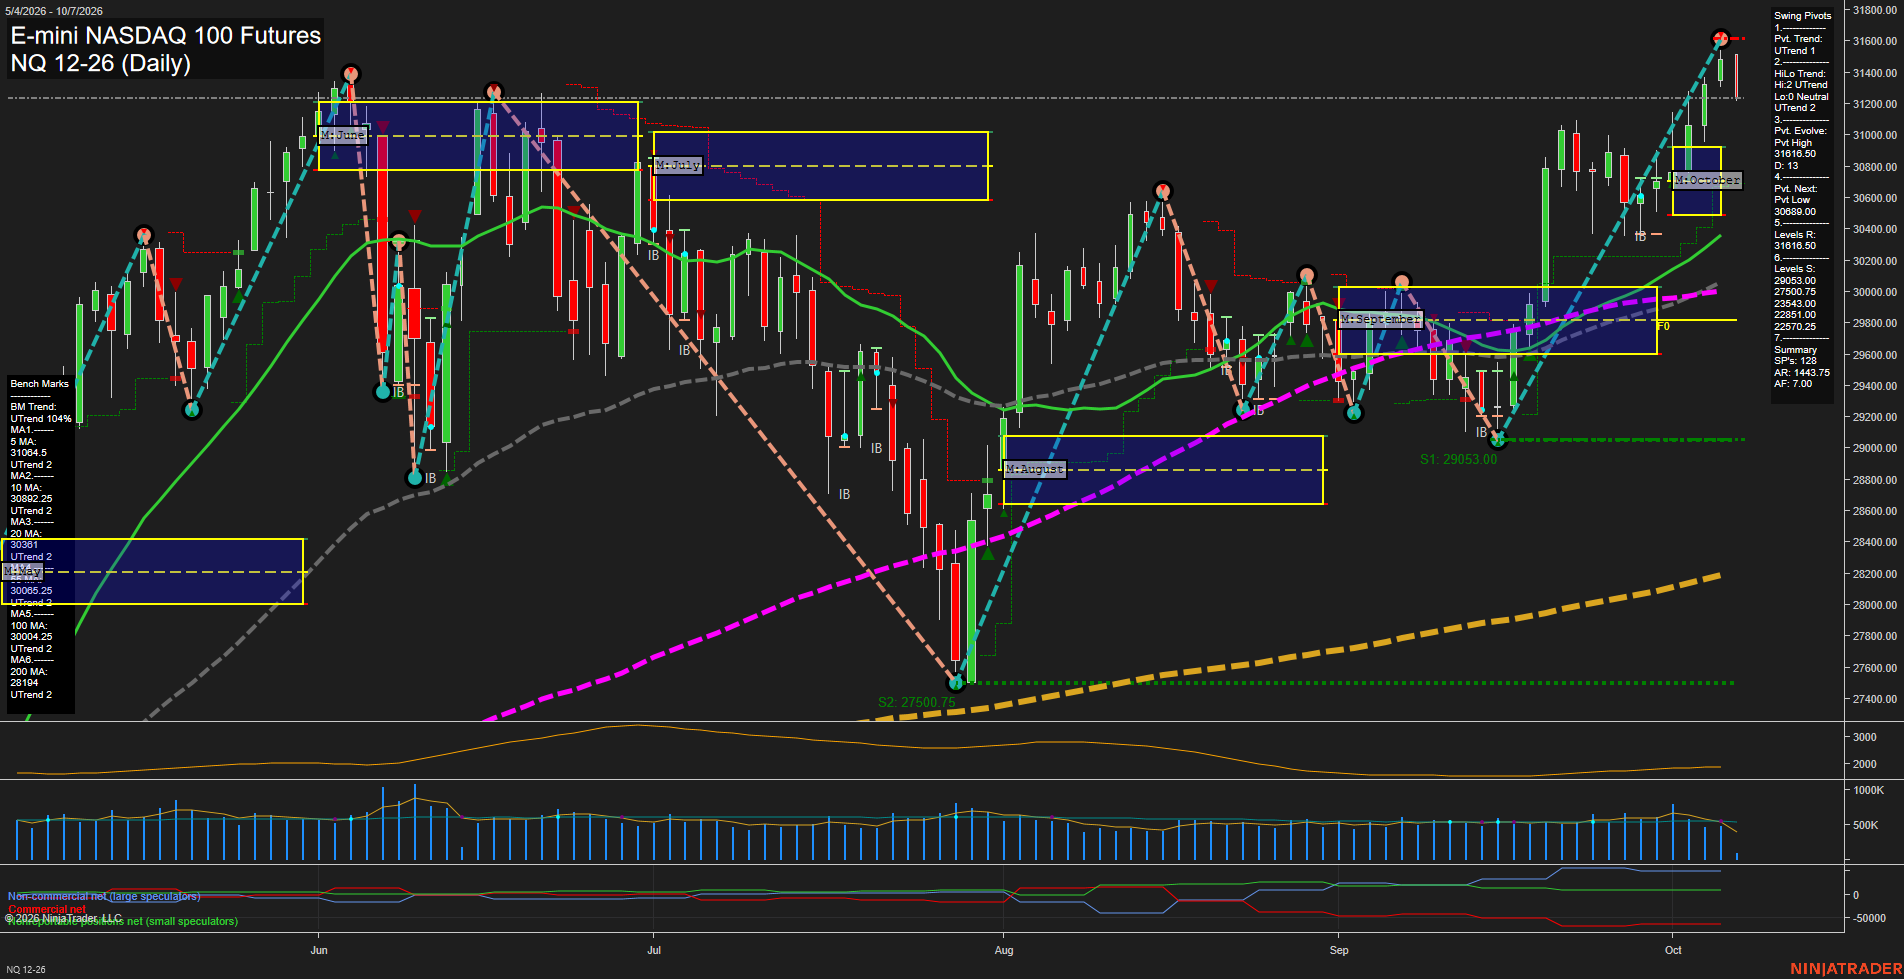
Overall Rating
- Short-Term: Bullish
- Intermediate-Term: Bullish
- Long-Term: Bullish.
Key Insights Summary
Price is in a broad bullish swing structure, holding above all daily benchmarks while weekly, monthly, and yearly Fib-grid bias remains above F0%. The advance from the September low has produced higher lows and higher highs, with the current pivot evolving as a high near 31616.50. Fast momentum and elevated ATR reflect an active expansion phase, while the 30689.00 pivot reversal level defines the nearest short-term structural transition point.
View charts on: AlphaWebTrader HTF Charts
CL Daily View
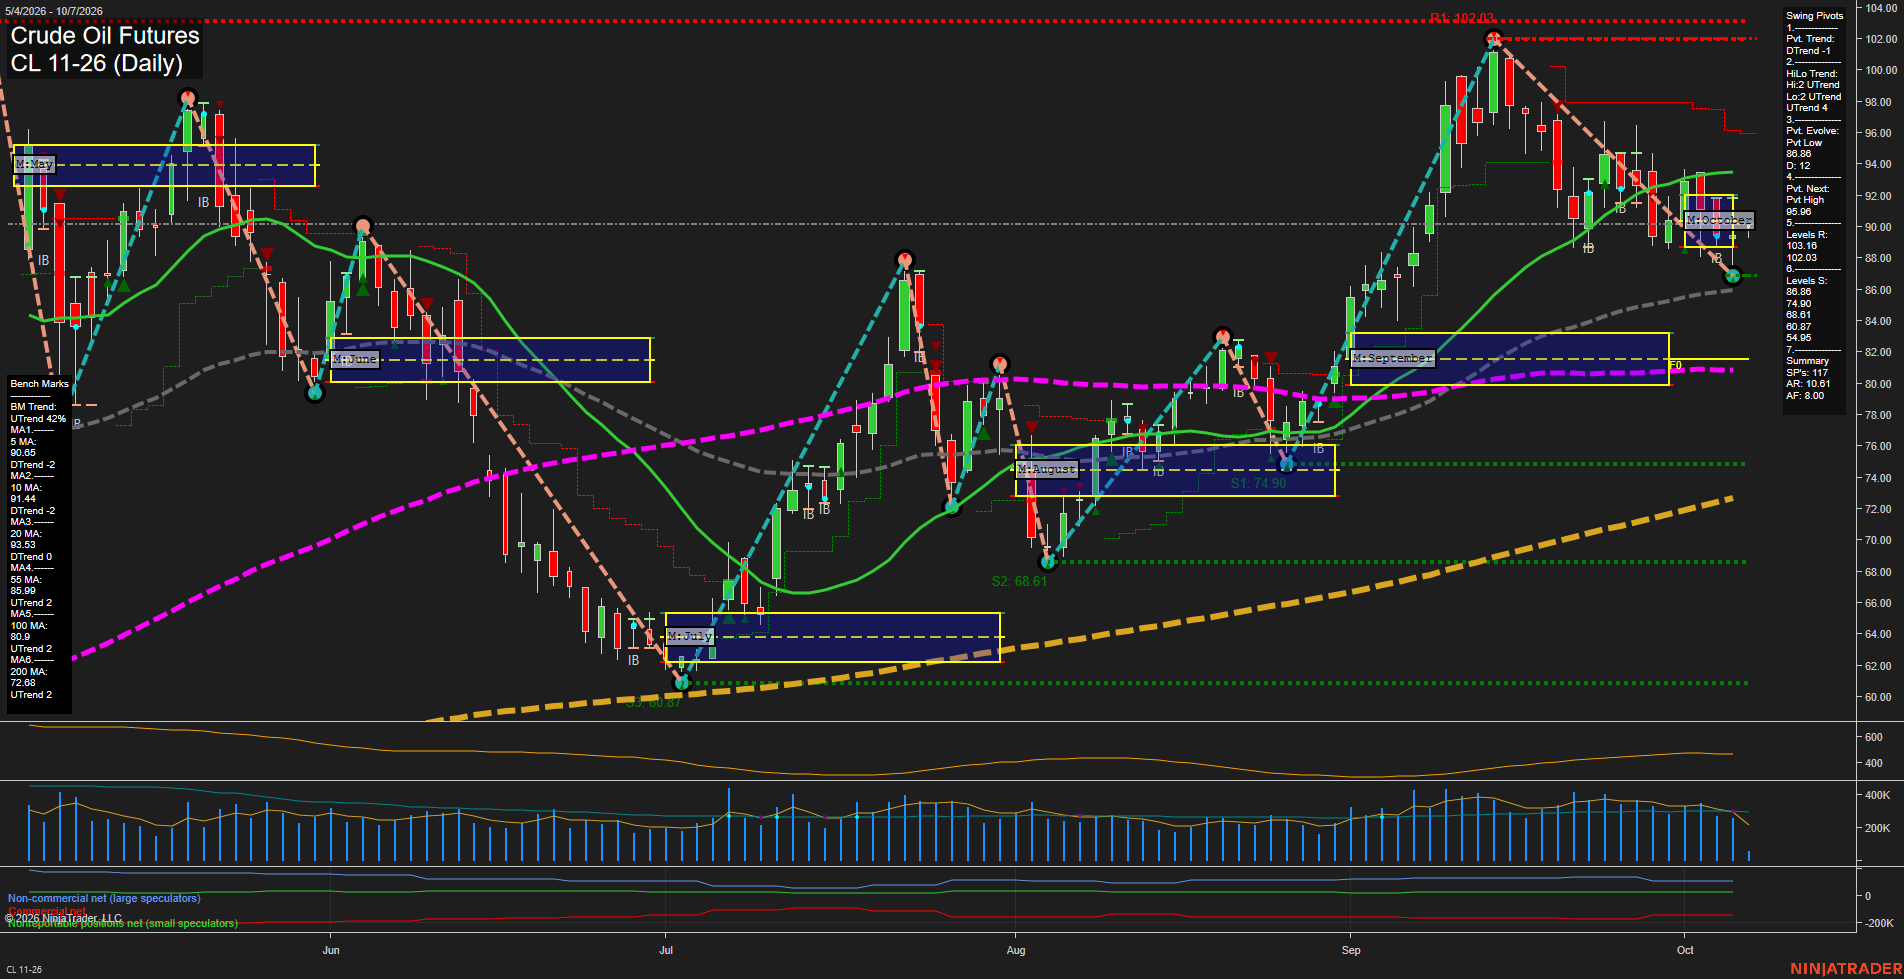
Overall Rating
- Short-Term: Bearish
- Intermediate-Term: Bullish
- Long-Term: Bullish.
Key Insights Summary
Price is consolidating near 90.56 after a sharp September rally to the 102.03 swing-high resistance zone and a subsequent pullback to the 86.86 pivot low. Short-term structure remains corrective: price is below the 5-, 10-, and 20-day benchmarks, the weekly grid is below F0%, and the active pivot trend is down. The intermediate structure remains constructive because the higher-low pivot sequence, monthly grid position above F0%, and rising 55-day benchmark remain intact. The chart is positioned between 86.86 support and 94.18 resistance, with 95.96 identified as the next pivot-high reversal level. Long-term trend conditions remain positive above the rising 100- and 200-day averages.
View charts on: AlphaWebTrader HTF Charts
GC Daily View
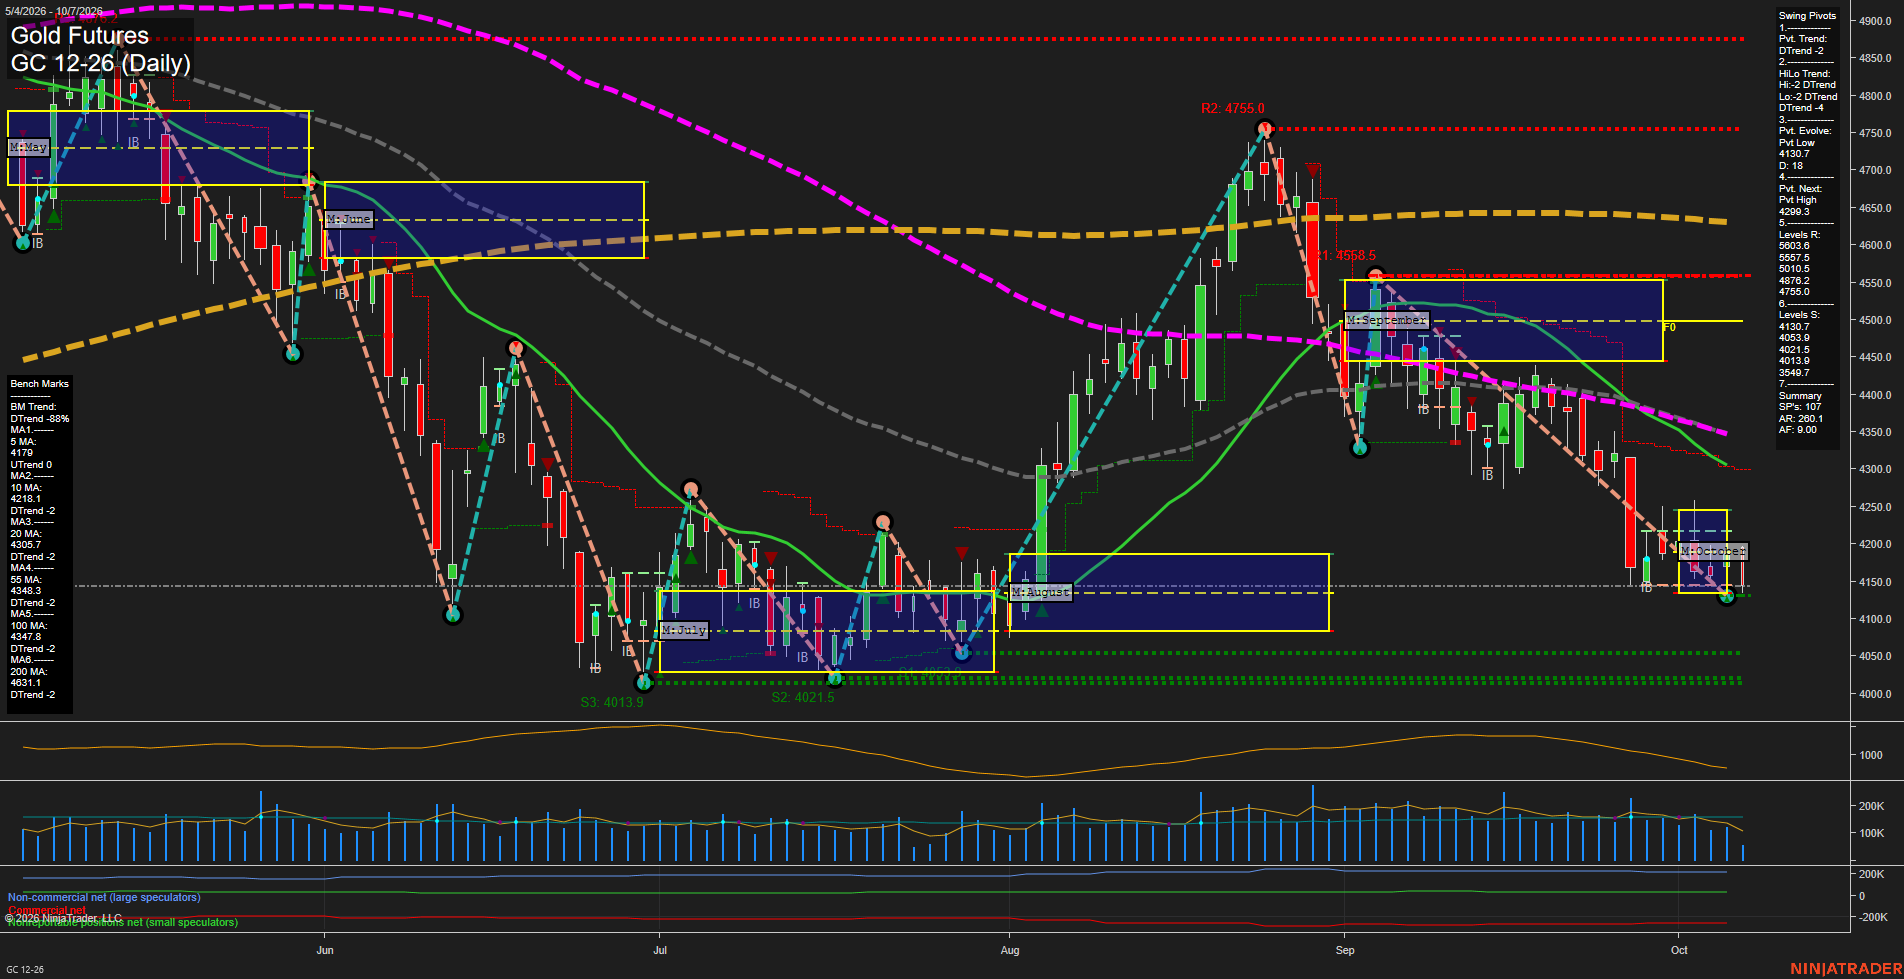
Overall Rating
- Short-Term: Bearish
- Intermediate-Term: Bearish
- Long-Term: Bearish.
Key Insights Summary
Price is consolidating near the 4130.7 pivot-low support after a sharp September decline, with small daily bars reflecting slower downside momentum rather than a confirmed reversal. The short-term 5-day average is rising, but price remains beneath the 10-, 20-, 55-, 100-, and 200-day benchmarks while both pivot structures and weekly, monthly, and yearly Fib-grid measures remain down. The dominant swing structure is lower highs and lower lows; 4299.3 is the next pivot-reversal reference, while 4130.7 and the clustered 4053.9-4013.9 supports define the nearby downside structure.
View charts on: AlphaWebTrader HTF Charts
ZB Daily View
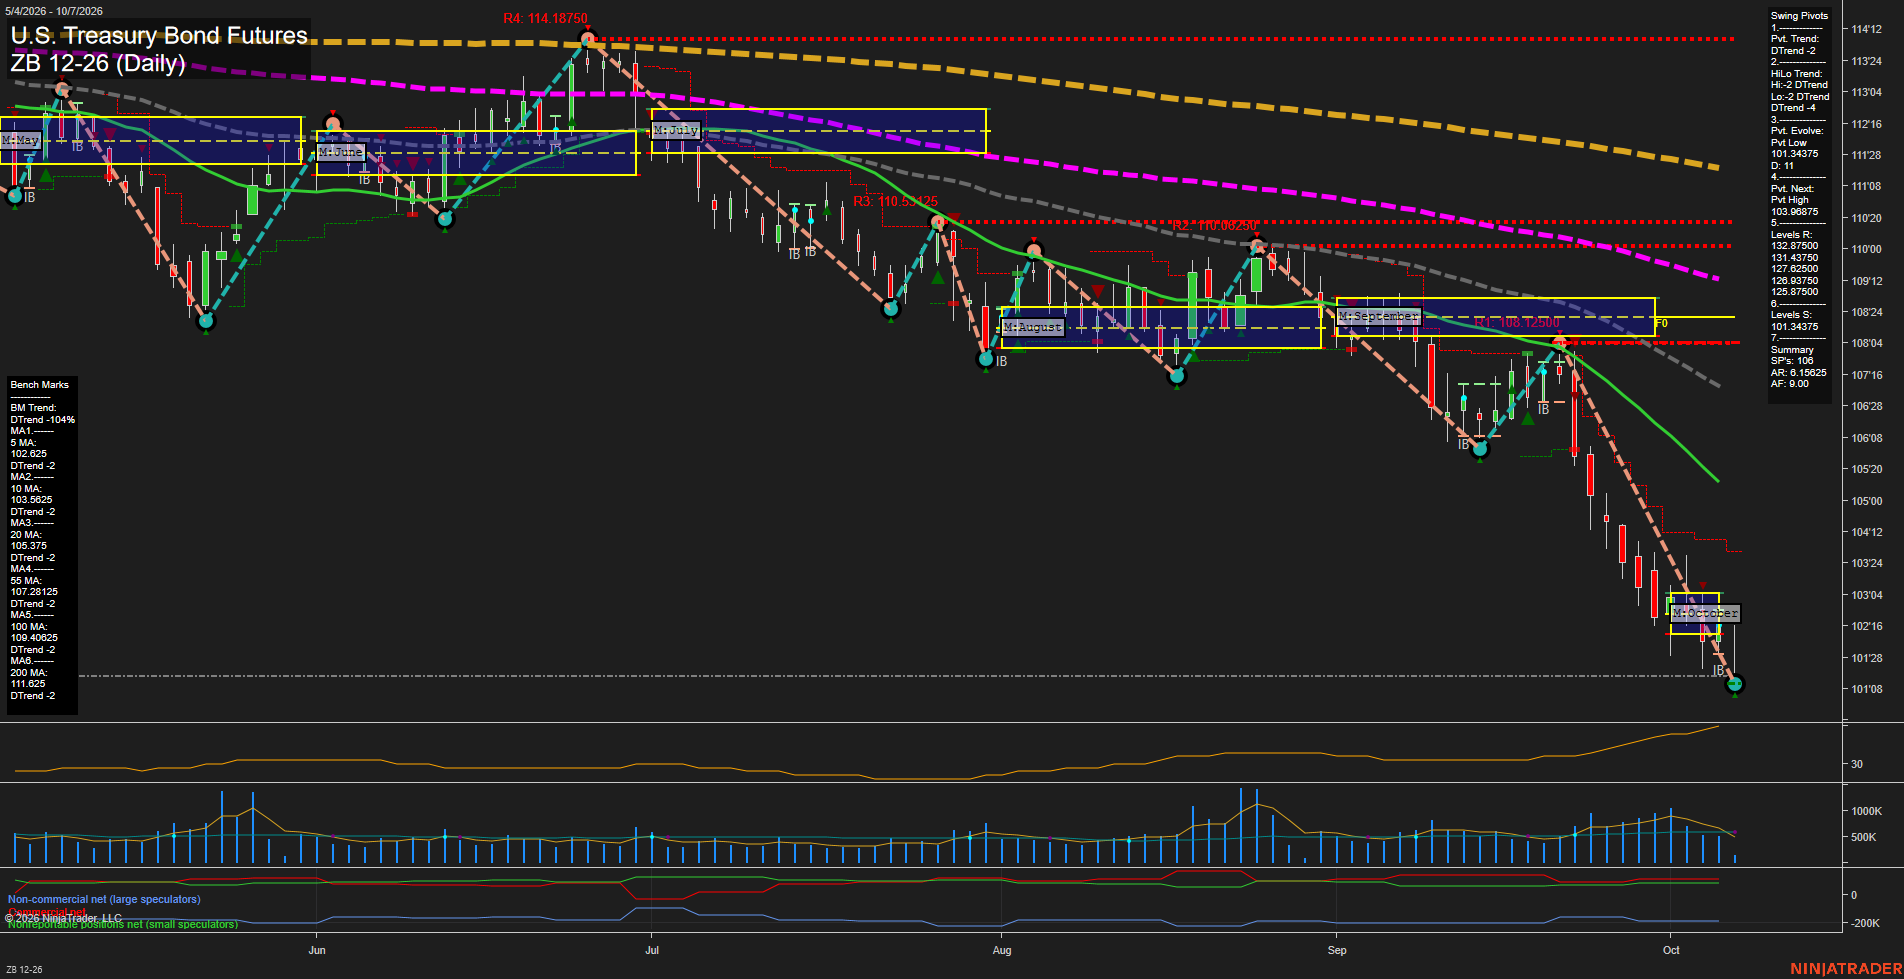
Overall Rating
- Short-Term: Bearish
- Intermediate-Term: Bearish
- Long-Term: Bearish.
Key Insights Summary
ZB is in a broad, synchronized bearish structure, with price below the weekly, monthly, and yearly Fib-grid centers and below every benchmark moving average. The decline is accelerating through large daily bars, while the pivot structure continues to show lower highs and lower lows. Price is pressing beneath the prior 101.34375 swing-low area, leaving 103.96875 as the nearest meaningful pivot-reversal reference. Elevated ATR and active volume characterize an expansionary selloff rather than a balanced consolidation, while the downward slope of the 20-, 55-, 100-, and 200-day averages confirms persistent intermediate- and long-term downside pressure.
View charts on: AlphaWebTrader HTF Charts