The Dow rose on strong earnings as tech lagged on AI financing concerns. Oil rebounded overnight, gold fell and Treasury yields declined in U.S. trading.
Fundamentals: Strong earnings and broader sector gains lifted the Dow 1.05%, while the Nasdaq finished flat amid concerns over AI financing and debt sustainability. Oil fell during the U.S. session before rebounding in early Asian trading on renewed Strait of Hormuz supply risks. Gold declined despite lower Treasury yields, while Asian equities advanced as inflation and borrowing costs remained in focus.
Technicals: Equity performance is mixed, with IWM and DIA advancing while AAPL and META decline. Daily and weekly futures charts show Dow resilience alongside corrective pressure in the S&P 500 and Nasdaq, while midcap and Russell 2000 daily trends remain bearish. The roundup examines ETF movers, benchmark averages, and key support and resistance levels across U.S. indices and Germany’s DAX.
After Market Close daily snapshot: market news summary and sentiment, major ETFs, Magnificent 7 analysis, Indices Futures Higher Time Frame Analysis, and E-mini S&P500, Nasdaq 100, NYMEX Crude, Gold Futures Daily Chart analysis.
As of: October 20, 2026 23:58 CT
Market News Summary:
Earnings supported the Dow while AI financing concerns restrained technology shares; an overnight oil rebound renewed inflation concerns.
Primary Drivers & Risks:
- Primary Driver: Strong earnings and broader equity leadership
- Primary Risk: AI debt concerns and renewed oil inflation
Tone:
Mixed, with improving equity sentiment offset by financing and energy risks.
Stock Market / ETFs / Indices:
The Dow gained 1.05%, or 548 points, to close at 52,513.98, while the Nasdaq finished flat. Gains extended beyond technology, with 3M, Northrop Grumman and Hasbro supporting the rally. AI spending, borrowing costs and debt sustainability remained concerns; CoreWeave fell more than 3% in Tuesday premarket trading. General Motors shares declined alongside a warning about a difficult 2027, despite a $20 billion repurchase announcement. Asian equities subsequently rebounded, with the Nikkei rising 1.8% in early trading.
Geopolitical:
Hopes for U.S.-Iran diplomacy accompanied Tuesday’s oil decline, but later reports of attacks on vessels in the Strait of Hormuz renewed supply concerns. China condemned the U.S. exclusion of DeepSeek products from government systems. The U.S. also discussed cooperation with Reliance Industries on refining Western energy supplies.
Oil / Energy:
Lower oil prices supported Wall Street during the U.S. session before crude rose in early Asian trading on Middle East supply worries. Airline industry commentary highlighted carriers absorbing much of the cost of jet fuel.
Gold / Metals:
Gold declined in late U.S. trading despite lower Treasury yields and extended its decline in early Asian trading as crude rebounded. Reports linked the pressure to persistent inflation concerns and further Fed tightening expectations. Silver rose in late U.S. trading, although later coverage highlighted renewed pressure on both metals.
Fed / Financials:
Treasury yields fell during late U.S. trading, but high borrowing costs and additional Fed tightening remained concerns in the coverage. A longer-term economist projection placed 10-year Treasury yields above 5% into 2027, distinct from the session’s yield movement. JPMorgan committed $5 billion in equity to companies focused on national security, defense technology and critical supply chains.
Macro / Other:
Housing activity weakened, while AI data center projects increased U.S. warehouse demand and rents. These reports showed real-economy support from AI investment alongside financial-market concerns about its funding and returns.
Conclusion:
Corporate earnings and broader sector participation lifted the Dow, while AI financing concerns limited technology performance. Lower oil prices supported the U.S. session, but that backdrop changed as crude rebounded overnight.
Hormuz supply disruptions and persistent inflation concerns remained key cross-currents for index futures. Asian equity gains contrasted with continued scrutiny of AI debt and elevated borrowing costs.
Market News Sentiment
Market News Articles: 67
- Negative: 44.78%
- Neutral: 28.36%
- Positive: 26.87%
Sentiment Summary: Among 67 market news articles, 45% were negative, 28% neutral, and 27% positive.
Conclusion: Negative sentiment was the largest category, exceeding positive sentiment by 18 percentage points.
GLD,Gold Articles: 16
- Positive: 43.75%
- Neutral: 31.25%
- Negative: 25.00%
Sentiment Summary: Across 16 GLD/gold articles, sentiment was 44% positive, 31% neutral, and 25% negative.
Conclusion: Positive sentiment was the largest category, but the snapshot contains no direct data on index futures sentiment.
USO,Oil Articles: 15
- Negative: 33.33%
- Positive: 33.33%
- Neutral: 33.33%
Sentiment Summary: Across 15 USO and oil articles, sentiment is evenly split at 33% negative, 33% positive, and 33% neutral.
Conclusion: The snapshot shows no dominant sentiment and provides no direct measure of indices futures sentiment.
ETF and stock performance
ETF, Mag7, and Cross-Market ETF Insights
Overall Tone
The daily session showed a broadly positive but uneven risk tone, with gains extending beyond the largest technology stocks.
Equity ETFs and Mag7
Small caps led as IWM rose 1.66%, while DIA and mid-caps outpaced SPY and QQQ edged lower. Mag7 performance was mostly weaker and aligned more closely with QQQ: Tesla stood out with a 1.54% gain, Amazon barely advanced, and Meta led the laggards with a 1.59% decline.
Cross-Market ETFs
Long-duration Treasuries and bitcoin gained, with TLT up 0.84% and IBIT up 0.89%, alongside the broader equity advance. Gold fell 0.54% and oil slipped slightly, diverging from the gains across most equity ETFs.
| Instrument | Close | Net change % | Vol | Vwap |
|---|---|---|---|---|
| IWM ▲ | 275.78 | +1.66% | 26,435,417 | 275.05 |
| DIA ▲ | 524.36 | +1.05% | 3,616,778 | 523.57 |
| IJH ▲ | 73.09 | +0.98% | 7,259,617 | 72.96 |
| SPY ▲ | 769.05 | +0.34% | 35,110,840 | 768.97 |
| QQQ ▼ | 717.63 | -0.10% | 30,713,352 | 717.93 |
| Average / total | — | +0.78% | 103,136,004 | — |
| Instrument | Close | Net change % | Vol | Vwap |
|---|---|---|---|---|
| TSLA ▲ | 373.71 | +1.54% | 32,588,463 | 373.03 |
| AMZN ▲ | 262.63 | +0.07% | 35,265,573 | 262.92 |
| NVDA ▼ | 216.47 | -0.29% | 80,281,632 | 216.34 |
| MSFT ▼ | 531.87 | -0.31% | 15,192,747 | 531.36 |
| AAPL ▼ | 339.50 | -1.00% | 36,598,474 | 340.34 |
| META ▼ | 694.25 | -1.59% | 17,115,742 | 690.34 |
| Average / total | — | -0.26% | 217,042,631 | — |
| Instrument | Close | Net change % | Vol | Vwap |
|---|---|---|---|---|
| IBIT ▲ | 46.71 | +0.89% | 32,627,087 | 46.74 |
| TLT ▲ | 80.13 | +0.84% | 28,479,020 | 80.09 |
| USO ▼ | 160.61 | -0.12% | 7,575,659 | 159.03 |
| GLD ▼ | 377.65 | -0.54% | 6,105,622 | 378.47 |
| Average / total | — | +0.27% | 74,787,388 | — |
Futures Indices – Higher Time Frame Analysis
Summary of the current state of US Indices Futures based on higher time-frame (HTF) technical analysis as of: 2026-10-20: 23:56 CT.
US Indices Futures
- ES YSFG upward, MSFG below F0%, declining short benchmarks, daily DTrend, support 7657–7676, pivot-next 7589.75, resistance 7824 and 7897.50–7906.25.
- NQ YSFG upward, MSFG below F0%, WSFG above F0%, below 5–100-day benchmarks, DTrend, support 29053–29226, pivot reversal 30197, resistance 31375.50–31616.50.
- YM above YSFG/MSFG/WSFG references, rising 5–20-day benchmarks, daily pivots upward, weekly pivots downward, support 50859, pivot reversal 53199, resistance 52835 and 55316.
- EMD YSFG upward, MSFG below F0%, WSFG midpoint consolidation, below all daily benchmarks, pivot/HiLo DTrend, support 3600.3–3609.1, resistance 3635.7 and 3737.8.
- RTY YSFG upward, MSFG below F0%, WSFG above F0%, below all daily benchmarks, bearish pivots, support 2723.3, pivot reversal 2803.5, benchmark resistance 2761–2822.
- FDAX YSFG/MSFG above F0%, WSFG below F0%, below 5/20-day benchmarks, short-term DTrend, support 24897–25170, 200-day benchmark 25273, resistance 25748–25827.
Overall State
- Short-Term: Bearish
- Intermediate-Term: Bearish
- Long-Term: Bullish
Conclusion
Short-term downside structures align across ES, NQ, EMD, RTY and FDAX; YM diverges with rising daily pivots and short benchmarks. MSFG weakness dominates ES, NQ, EMD and RTY, while YM and FDAX retain firmer monthly structures. Rising yearly grids and longer weekly benchmarks preserve the broader upward context, despite bearish daily structures in EMD and RTY. Recent ES short signals and NQ’s reversal reinforce corrective conditions; nearby pivot supports and overhead benchmark clusters define the current consolidation ranges.
Note: Intra-day counter-trend pullbacks or retracements may occur, HTF is context for informational usage and market structure. Glossary: Session Fib Grids periods of YSFG:’Yearly’, MSFG:’Monthly’, WSFG:’Weekly’
For full details visit: AlphaWebTrader Technicals
ES Daily View
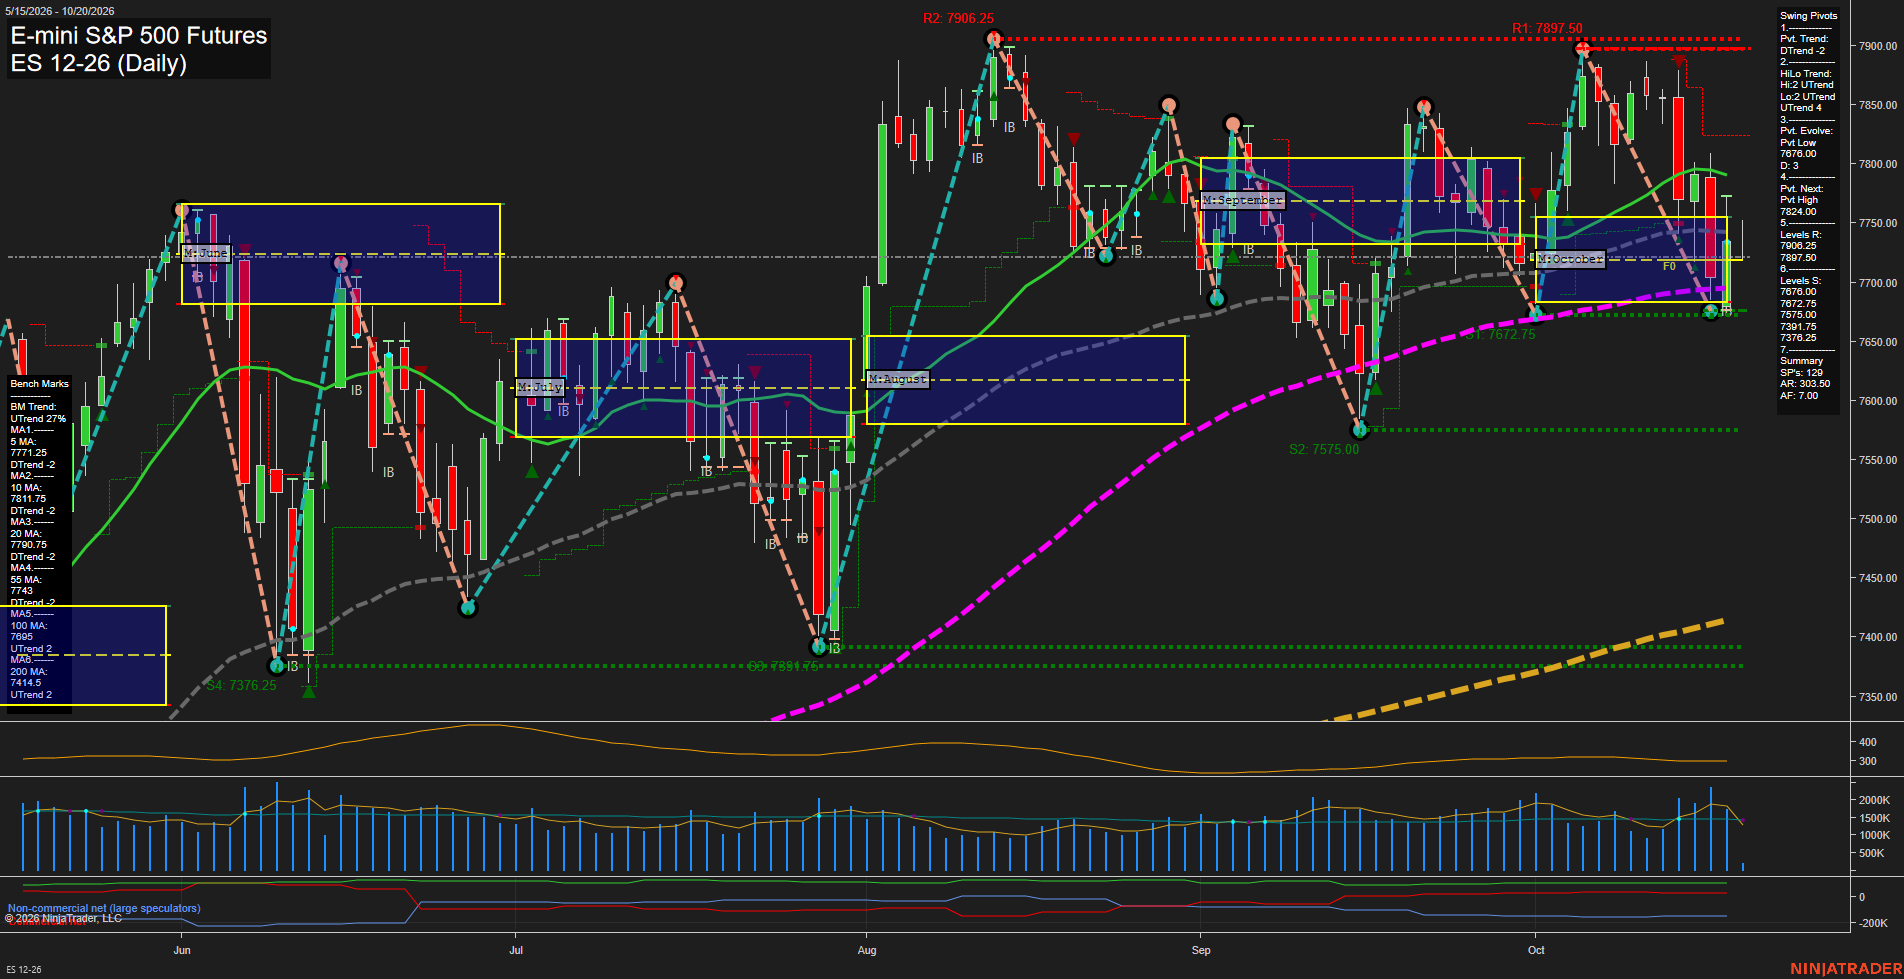
Overall Rating
- Short-Term: Bearish
- Intermediate-Term: Bearish
- Long-Term: Bullish.
Key Insights Summary
The daily structure reflects a short-term corrective downswing within a still constructive long-term advance. Price is below the 5, 10, 20, and 55-day benchmarks, while the pivot trend is DTrend and October MSFG remains below its F0% reference. The 7676 to 7657 support cluster has contained the latest selloff, producing a modest bounce, but momentum remains slow and price is still beneath nearby benchmark resistance. The intermediate HiLo trend remains positive and price holds above rising 100-day and 200-day averages, preserving the broader bullish structure. The current pattern is a volatile consolidation between support near 7676 and overhead pivot resistance at 7824, with major resistance concentrated near 7897.50 to 7906.25.
View charts on: AlphaWebTrader HTF Charts
NQ Daily View
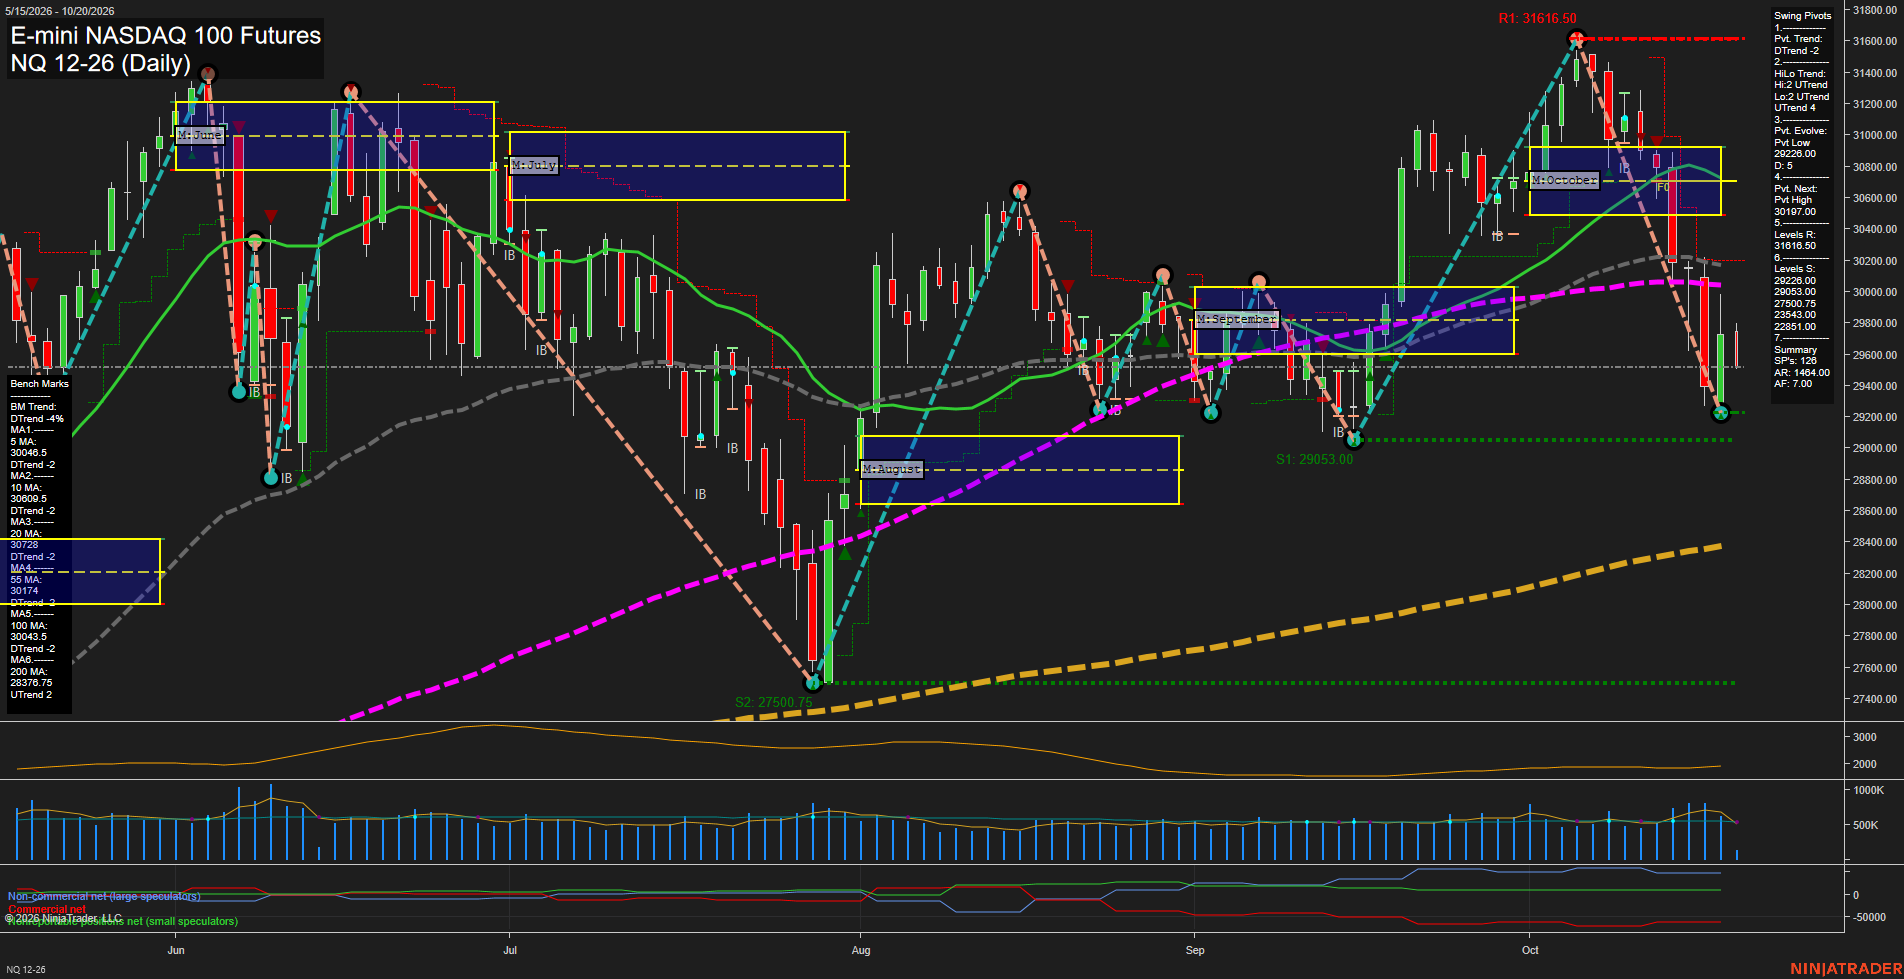
Overall Rating
- Short-Term: Bearish
- Intermediate-Term: Bearish
- Long-Term: Neutral.
Key Insights Summary
Price is rebounding from the 29226-29053 support zone after a sharp October decline, but the daily swing structure remains in a short-term DTrend and price remains beneath all benchmark averages from the 5-day through 100-day. The monthly grid remains below F0% and the clustered 30043-30728 moving-average area defines overhead countertrend resistance, with 30197 the next pivot reversal level. The broader yearly structure and rising 200-day average remain constructive, creating a mixed long-term backdrop while the current daily cycle is a volatile pullback from the 31616.50 swing high.
View charts on: AlphaWebTrader HTF Charts
CL Daily View
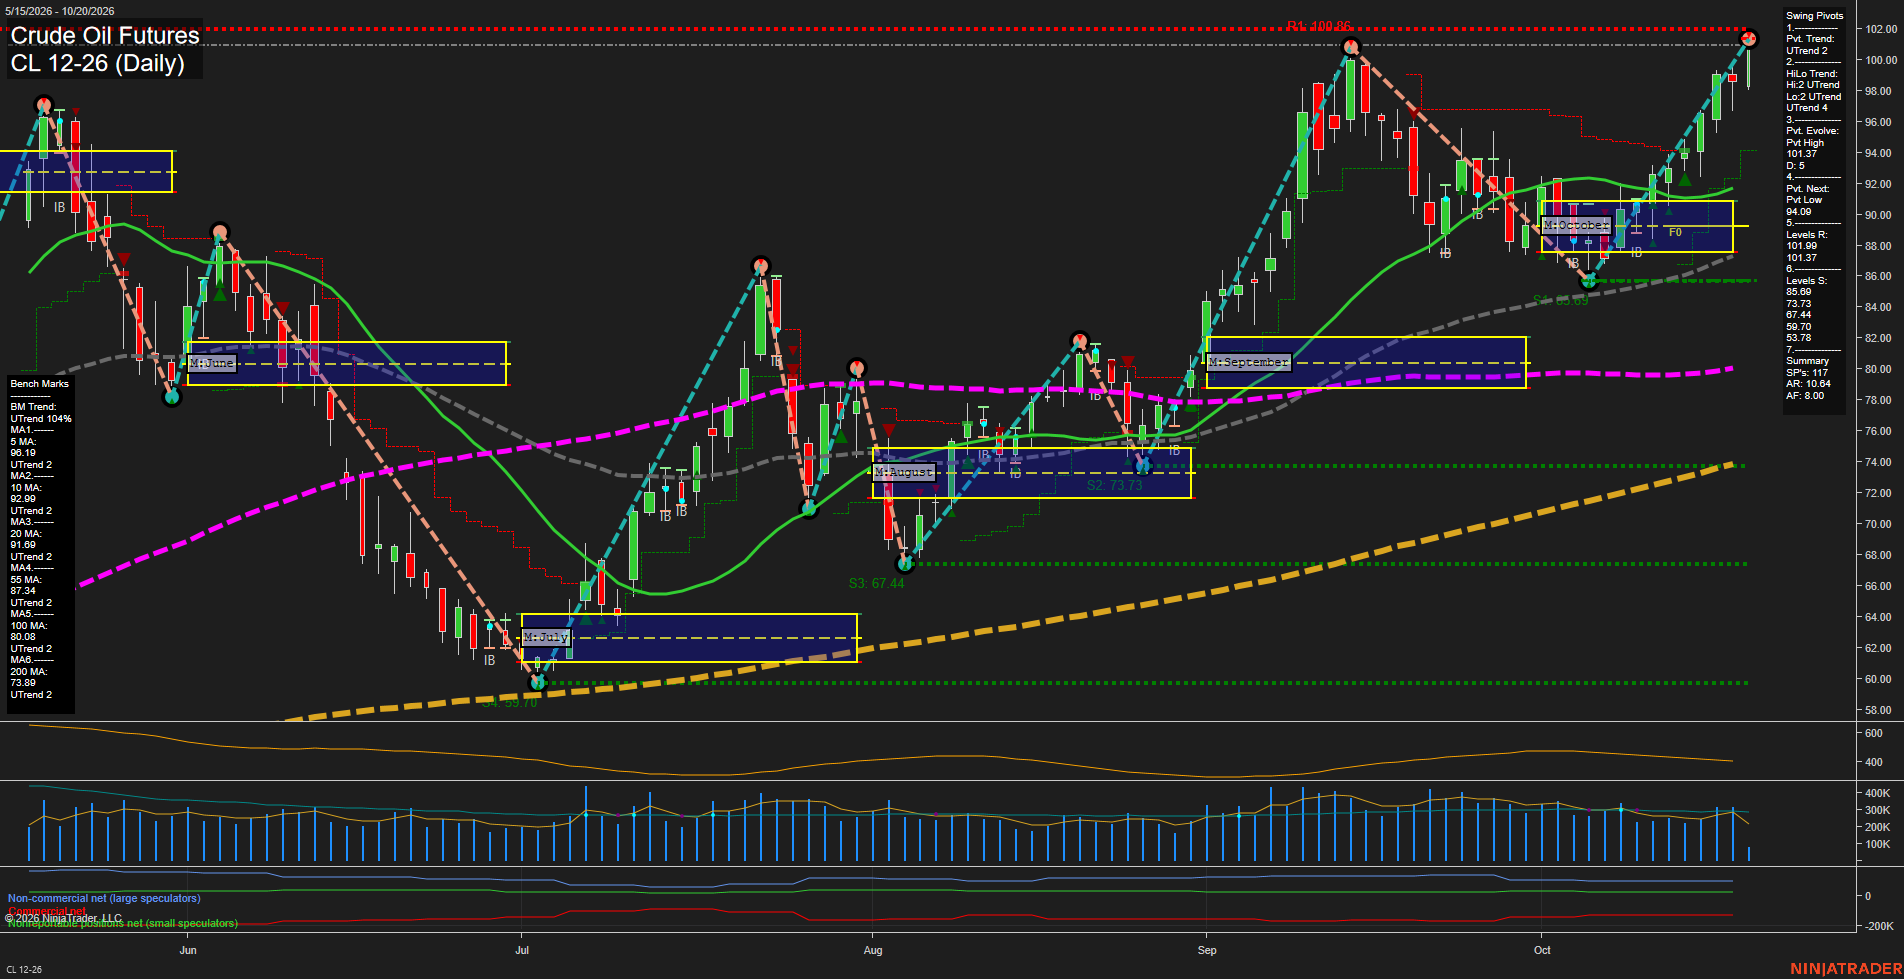
Overall Rating
- Short-Term: Bullish
- Intermediate-Term: Bullish
- Long-Term: Bullish.
Key Insights Summary
Price is in a broad multi-month advance, with higher pivot lows and a renewed push into the 100.86 to 101.37 resistance zone. Momentum is fast following the October recovery from the 85.69 support area, while price remains above every daily benchmark from the 5-day through 200-day average. The short-term pivot structure is bullish, though the active pivot-high area defines the immediate overhead test. Weekly, monthly, and yearly Fib-grid readings are all above their F0%/NTZ reference areas, aligning the short-, intermediate-, and long-term trend structure to the upside.
View charts on: AlphaWebTrader HTF Charts
GC Daily View
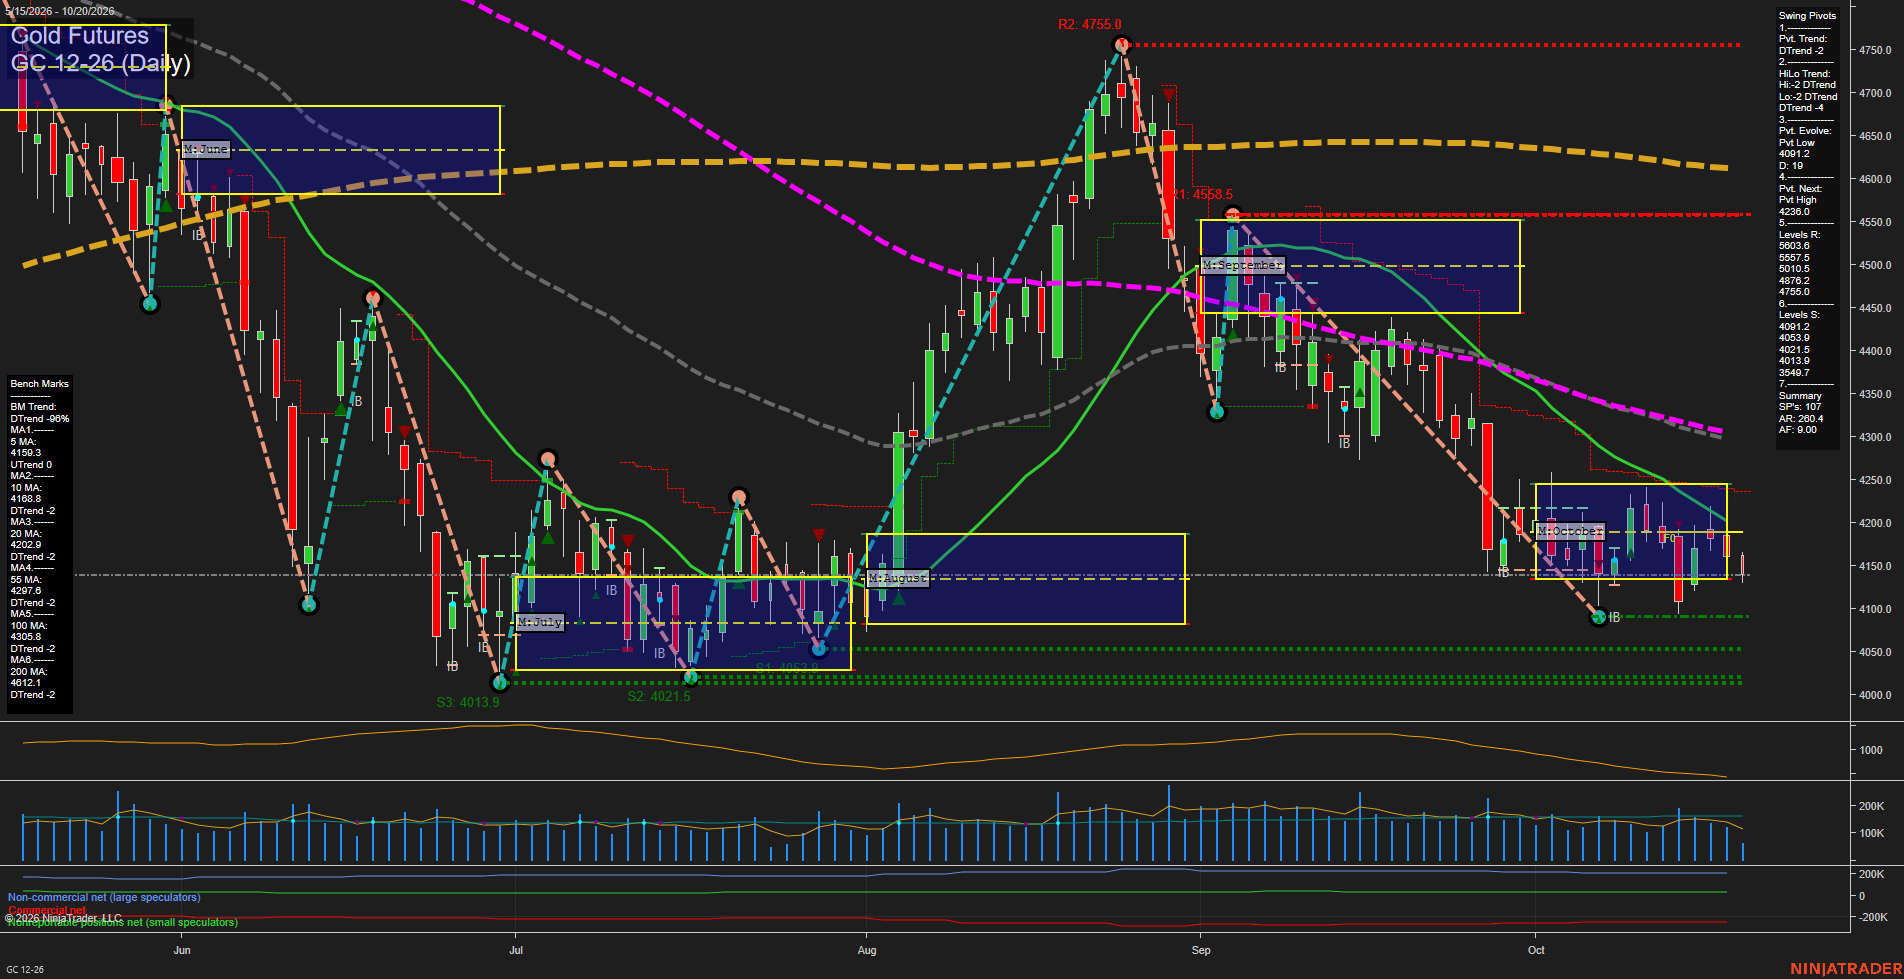
Overall Rating
- Short-Term: Bearish
- Intermediate-Term: Bearish
- Long-Term: Bearish.
Key Insights Summary
GC is in a broad daily-chart decline, with price beneath the weekly, monthly, and yearly Fib-grid centers and below every benchmark moving average except for a marginally rising 5-day average. The pivot structure remains bearish, defined by lower highs and lower lows from the late-August peak, while the current October consolidation is holding above the 4091.2 pivot low. The 4138 area is below the 5-, 10-, and 20-day averages, reinforcing weak short-term participation. A move through the evolving 4091.2 low would extend the established downside sequence toward clustered supports at 4053.9 to 4013.9, while 4236.0 is the next pivot-reversal reference and initial structural resistance. ATR remains elevated, reflecting a volatile correction/consolidation phase following the sharp September selloff.
View charts on: AlphaWebTrader HTF Charts
ZB Daily View
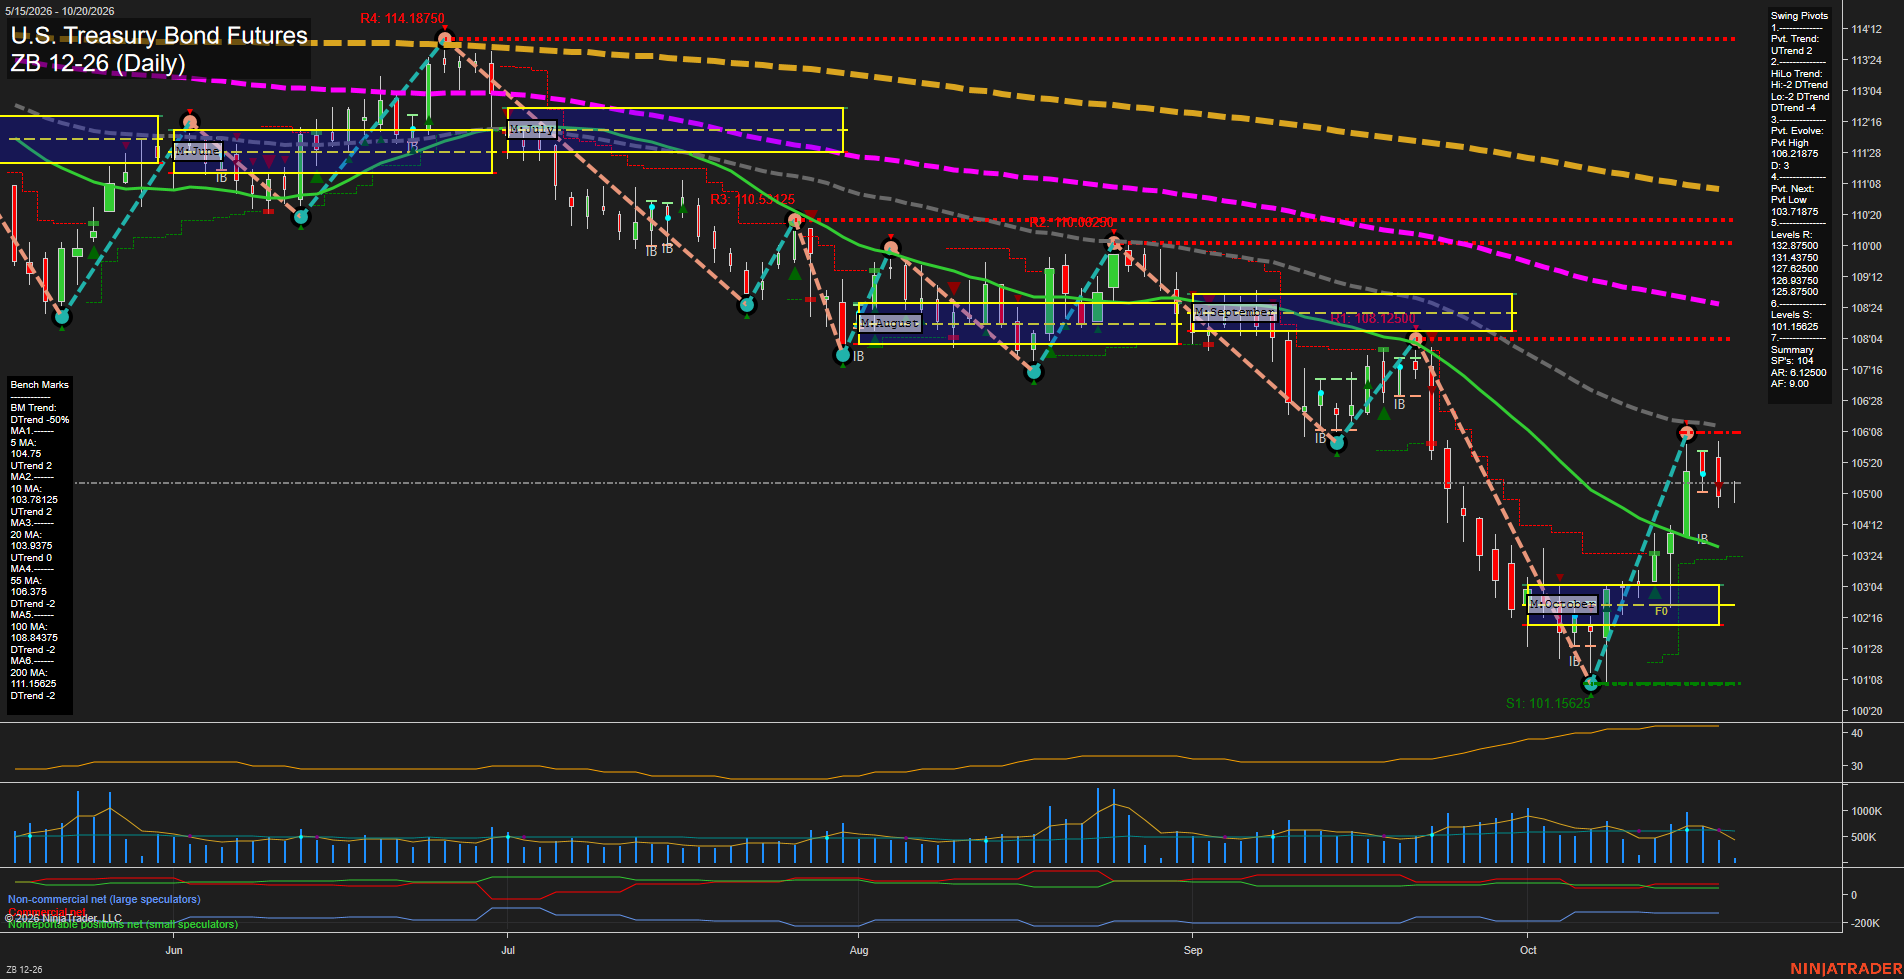
Overall Rating
- Short-Term: Bullish
- Intermediate-Term: Neutral
- Long-Term: Bearish.
Key Insights Summary
Price remains in a short-term recovery structure following the October washout near 101'05, supported by an UTrend pivot condition and rising 5, 10, and 20-day benchmarks. The rebound stalled beneath the 55-day benchmark and the 106'23 pivot high, producing a pullback from the recent recovery peak. Weekly fib positioning remains below its F0%/NTZ area, while the monthly grid remains constructive above its F0% level. The intermediate picture is mixed as the monthly trend is up but the HiLo pivot structure remains in a DTrend. Longer-term structure remains bearish, with price below the declining 55, 100, and 200-day benchmarks and the yearly grid below equilibrium. Volume is moderate relative to the recent rebound, while ATR near 35 reflects an active but contained daily swing environment.
View charts on: AlphaWebTrader HTF Charts