U.S. and global futures show short-term weakness as Fed uncertainty, near-5% Treasury yields, Saudi oil disruption and AI earnings risk weigh on markets.
Fundamentals: U.S. index futures enter a week shaped by Saudi pipeline disruption, elevated fuel costs and Fed policy uncertainty. Markets price an 87% probability of a 25-basis-point rate hike as sticky inflation and 10-year Treasury yields near 5% pressure equity valuations. Oil, diesel and geopolitical risks remain in focus alongside concentrated AI-driven earnings growth.
Technicals: U.S. index futures and major global contracts begin the week with bearish short-term and intermediate-term technical structures following recent selloffs and failed rebounds. The S&P 500, Nasdaq, Dow, Russell 2000, E-mini Dow and DAX remain within broader long-term uptrends, supported by yearly grid readings and longer-term averages. Amazon, Apple and Alphabet led prior-session ETF movers, while oil declined.
Market Week Ahead – Trading 360° view Market Radar for: holidays, earnings, eco-news, market-news summary, news sentiment, and major ETFs, MAG7, Higher Time Frame Analysis Indices Futures Summary, and ETF SPY S&P500, QQQ Tech, USO Oil, GLD Gold Weekly Chart analysis
As of: September 13, 2026 06:15 CT
EcoNews Radar U.S. Events
| Day | Time | Impact | Event |
|---|---|---|---|
| Wed | 08:30 | Medium | Core Retail Sales m/m |
| Wed | 08:30 | Medium | Retail Sales m/m |
| Wed | 10:30 | Low | Crude Oil Inventories |
| Wed | 14:00 | High | Federal Funds Rate |
| Wed | 14:00 | High | FOMC Economic Projections |
| Wed | 14:00 | High | FOMC Statement |
| Wed | 14:30 | High | FOMC Press Conference |
| Thu | 08:30 | Medium | Philly Fed Manufacturing Index |
| Thu | 08:30 | Medium | Unemployment Claims |
EcoNews Summary
Wednesday centers on the Federal Reserve policy decision and related communications, the week’s listed high-impact catalysts for U.S. index futures. The 14:00 Federal Funds Rate, FOMC Economic Projections, and FOMC Statement are followed by the 14:30 FOMC Press Conference. These releases frame the Fed’s policy stance, economic outlook, and inflation assessment. Low-impact crude oil inventories are included because inventory changes inform petroleum supply conditions and energy-price sensitivity. Thursday’s listed medium-impact data are excluded because they are not directly related to oil or petroleum supply.
Event Notes:
- Wednesday 10:30 – Crude Oil Inventories: Weekly change in U.S. commercial crude oil stockpiles. Traders monitor the report for petroleum supply conditions and potential energy-price pressure.
- Wednesday 14:00 – Federal Funds Rate: The Federal Reserve’s target range for overnight interest rates. It defines the current policy-rate setting and influences interest-rate-sensitive market pricing.
- Wednesday 14:00 – FOMC Economic Projections: Federal Reserve participants’ projections for growth, unemployment, inflation, and the policy-rate path. Markets monitor the release for the Committee’s economic and rate-policy outlook.
- Wednesday 14:00 – FOMC Statement: The formal policy statement outlining the Federal Reserve’s decision, economic assessment, and balance-of-risks language. Traders monitor wording changes for shifts in the policy stance.
- Wednesday 14:30 – FOMC Press Conference: The Chair’s remarks and question-and-answer session following the policy decision. It provides context on the statement, projections, and policy deliberations.
Conclusion:
The single most important day is Wednesday, led by the 14:00 Federal Funds Rate decision and accompanying FOMC materials, followed by the 14:30 press conference. Market momentum and volume often slow ahead of major FOMC events, with increased volatility at release time.
For full details visit: Forex Factory EcoNews
Market News Summary:
Energy-supply disruptions, elevated rates, and Fed policy focus dominate the futures backdrop.
Primary Drivers & Risks:
- Primary Driver: Saudi pipeline outage and fuel shortages
- Primary Risk: Fed hike and near-5% yields
Tone:
Cautious, with inflationary energy pressure and policy uncertainty.
Stock Market / ETFs / Indices:
S&P 500 futures trade ahead of the Fed decision. Recent index resilience followed hot inflation data, while technical commentary cited a reversal pattern after Thursday capitulation action. AI investment accounts for roughly half of S&P 500 earnings growth, concentrating earnings sensitivity among a limited group of major spenders.
Geopolitical:
The Iran conflict is disrupting Strait of Hormuz trade and extending pressure across oil and fuel markets. Concerns also include the duration of the conflict and vulnerability of Saudi energy infrastructure.
Oil / Energy:
A Saudi pipeline outage threatens up to 4% of global oil supply if pumping does not resume within days. Record diesel prices reflect refinery disruptions and constrained refining capacity, while U.S. diesel reached $6.20 per gallon amid broader supply-chain cost pressure.
Gold / Metals:
Currency-debasement concerns support attention on gold, while Bitcoin has recently shown a high correlation with the metal.
Fed / Financials:
Markets price an 87% probability of a 25-basis-point Fed rate hike after strong inflation and payroll data. Sticky inflation and 10-year Treasury yields near 5% remain central pressures for equities, while higher long-term yields tighten financial conditions.
Macro / Other:
AI-development concerns have introduced near-term uncertainty around jobs, data centers, and profitability, although infrastructure investment and automation demand remain active themes. Seasonal September weakness is also noted in equity-market commentary.
Conclusion:
Saudi supply disruption, record diesel prices, and the Fed decision are the main near-term drivers. Oil and refined-product constraints reinforce the inflation backdrop.
Near-5% Treasury yields pressure stock valuations as markets assess a potential rate hike. AI-led earnings concentration and geopolitical energy risks add cross-currents for index futures.
Market News Sentiment
Market News Articles: 6
- Neutral: 66.67%
- Negative: 33.33%
Sentiment Summary: News sentiment is predominantly neutral at 67%, with 33% negative coverage and no positive articles.
Conclusion: The news flow presents a neutral-to-cautious tone for indices futures day traders.
GLD,Gold Articles: 1
- Neutral: 100.00%
Sentiment Summary: GLD/Gold coverage was 100% neutral across 1 article.
Conclusion: The snapshot indicates no directional sentiment bias from the available GLD/Gold news coverage.
USO,Oil Articles: 4
- Positive: 50.00%
- Negative: 25.00%
- Neutral: 25.00%
Sentiment Summary: USO/Oil coverage is mixed-to-positive, with 50% positive, 25% negative, and 25% neutral articles.
Conclusion: Oil-related news tone is moderately positive but includes notable negative and neutral coverage relevant to indices futures.
SPY Weekly View
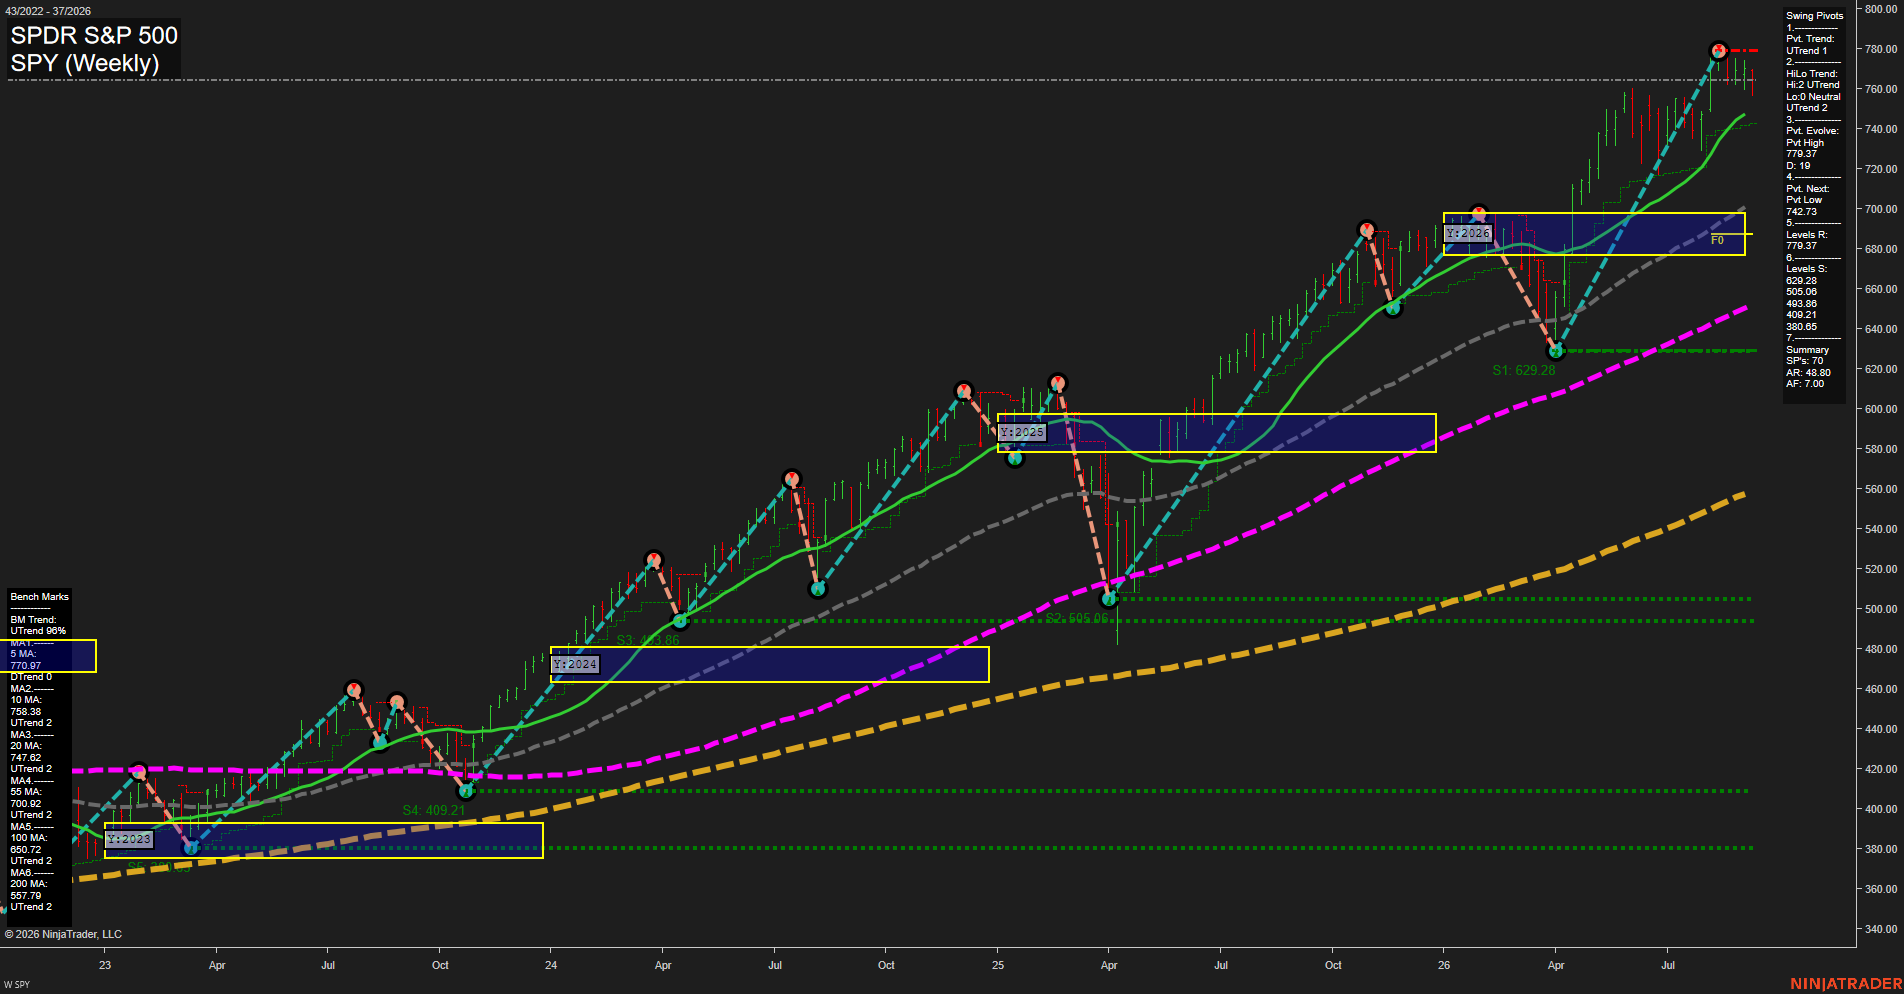
Overall Rating
- Short-Term: Bullish
- Intermediate-Term: Bullish
- Long-Term: Bullish.
Key Insights Summary
The futures swing-trader structure remains broadly constructive: weekly pivot and HiLo trends are both advancing, price holds above every benchmark average, and the moving-average stack is positively aligned. The market is consolidating near the 779.37 pivot-high resistance after a strong advance, with 742.73 defining the nearest swing-pivot reversal level. The current price is materially above the 2026 yearly NTZ/F0% area near 690-700, reflecting sustained upside extension rather than a neutral value-area rotation. A break above the recent high would represent trend continuation, while rotation beneath 742.73 would shift the short-term swing structure toward a deeper pullback within the still-bullish intermediate and long-term trend.
View charts on: AlphaWebTrader HTF Charts
QQQ Weekly View
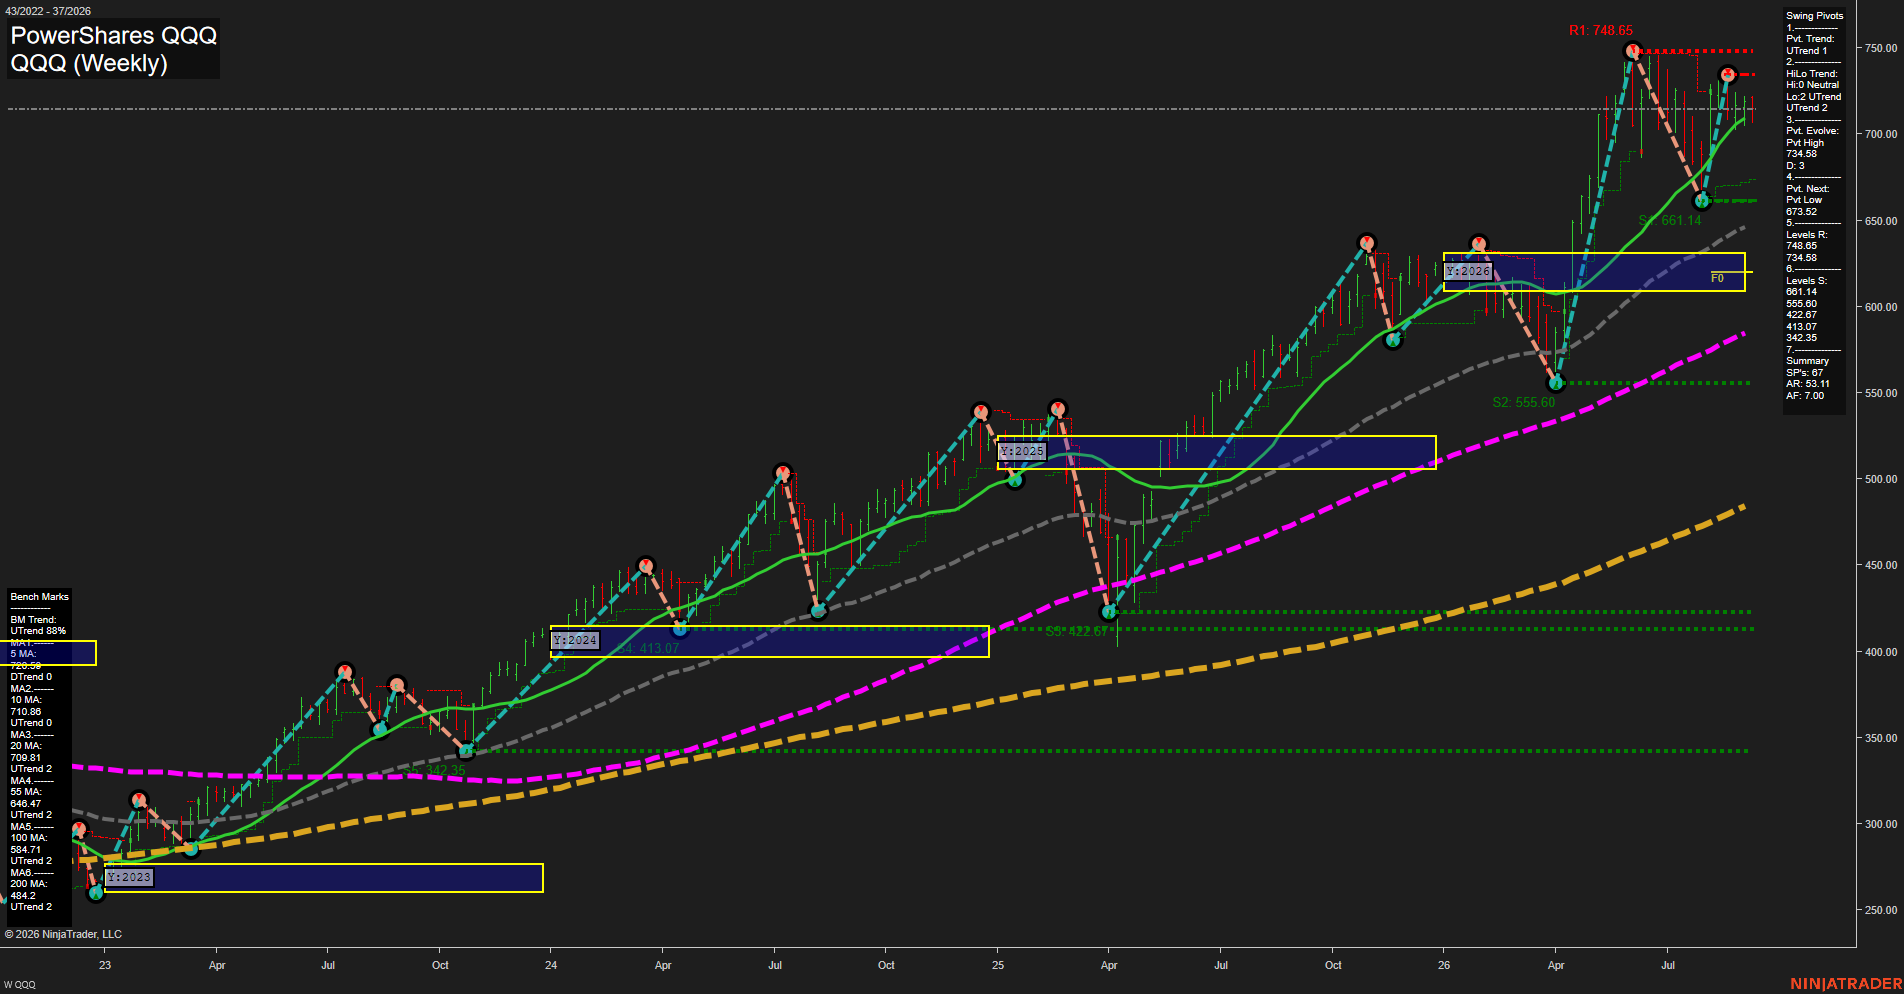
Overall Rating
- Short-Term: Bullish
- Intermediate-Term: Bullish
- Long-Term: Bullish.
Key Insights Summary
QQQ retains a broad weekly futures-style bullish structure, with price holding above the rising 10, 20, 55, 100, and 200-period benchmarks. The active pivot sequence is upward, although the intermediate HiLo structure remains neutral because the market is trading beneath the 748.65 prior swing-high resistance. The rebound from 555.60 produced a strong V-style recovery into the 734.58 pivot high; current bars show consolidation beneath the 734.58 to 748.65 resistance band. The 673.52 pivot-next level and 661.14 support define the nearer pullback structure, while 555.60 remains the major intermediate swing support. Price is materially above the 2026 yearly NTZ and F0% area near the low-600s, confirming long-term upside extension and a positive major trend.
View charts on: AlphaWebTrader HTF Charts
USO Weekly View
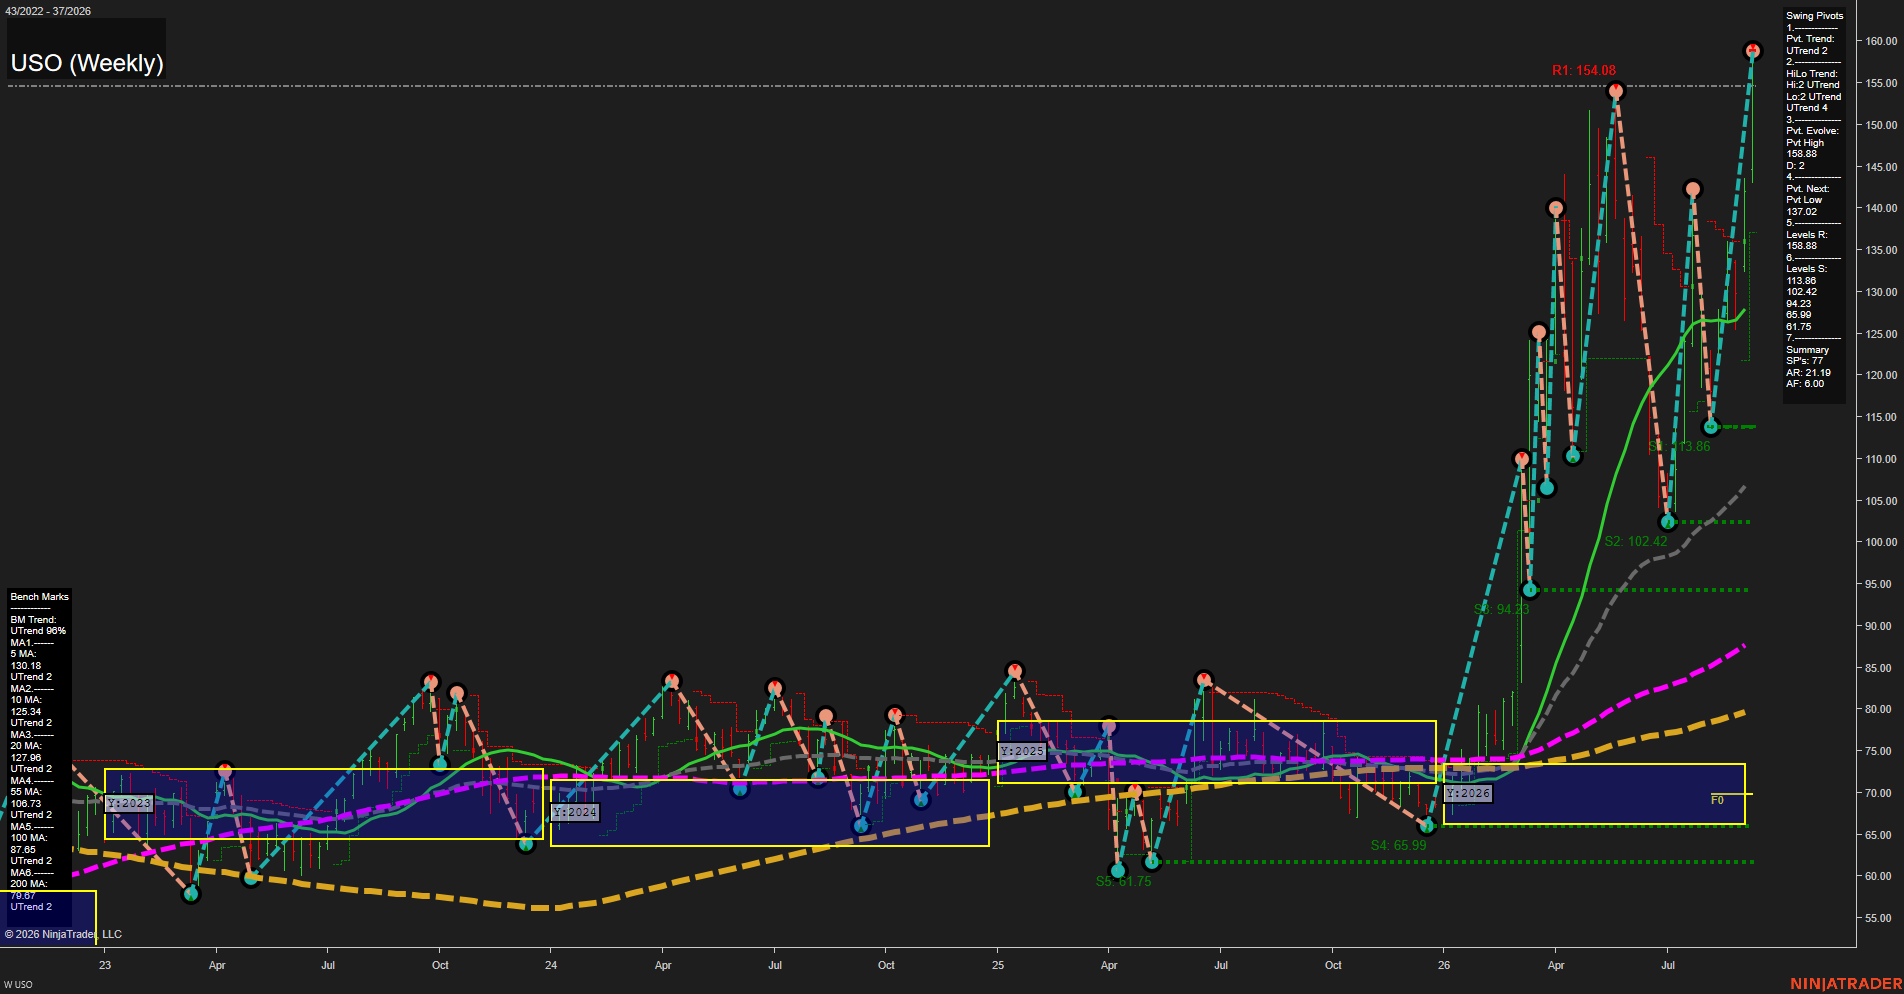
Overall Rating
- Short-Term: Bullish
- Intermediate-Term: Bullish
- Long-Term: Bullish.
Key Insights Summary
USO displays a strongly bullish weekly structure consistent with a futures swing-trader trend expansion: price is materially above the 2026 yearly NTZ/F0% area and all six benchmark averages are rising. The recent rebound from the 113.86 pivot support has restored fast upside momentum, while 137.02 defines the near-term pivot-reversal threshold. The 158.88 pivot high remains the major overhead reference. Intermediate and long-term structure retain higher-high and higher-low characteristics, with 127.96 to 130.18 forming the nearest moving-average trend zone and 113.86 the principal visible swing-support shelf.
View charts on: AlphaWebTrader HTF Charts
GLD Weekly View
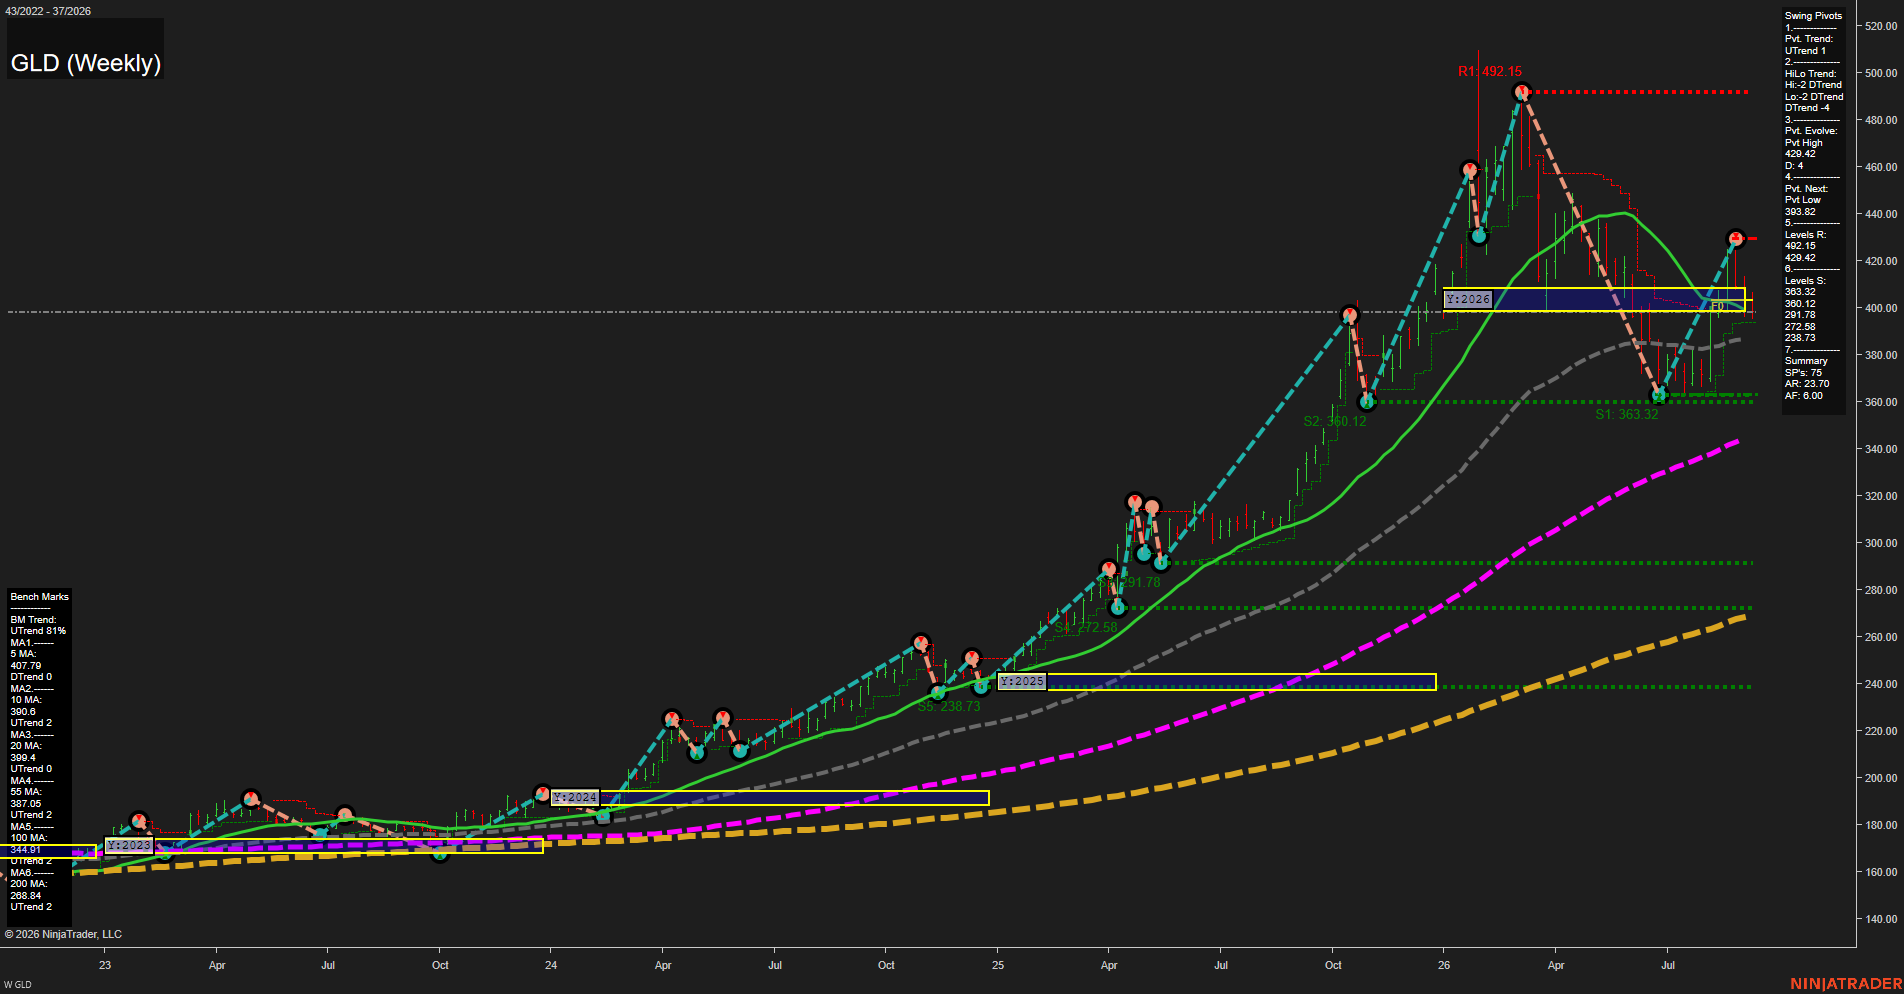
Overall Rating
- Short-Term: Neutral
- Intermediate-Term: Bullish
- Long-Term: Bullish.
Key Insights Summary
GLD, as a liquid gold-futures proxy, is recovering sharply from the 360.12-363.32 swing-support zone and has returned to the 2026 yearly F0%/NTZ area near 399. Price remains above the rising 10-, 20-, 55-, 100-, and 200-period benchmarks, preserving the broader bullish structure, while the declining 5-period average and intermediate DTrend reflect a recent corrective phase. The active short-term pivot remains an UTrend, but 429.42 is the defining pivot-high resistance before the larger 449.42 resistance. The current structure is a volatile V-shaped rebound within a broader consolidation below the 492.15 peak, with 393.82 serving as the nearby pivot-reversal reference.
View charts on: AlphaWebTrader HTF Charts
ZB Weekly View
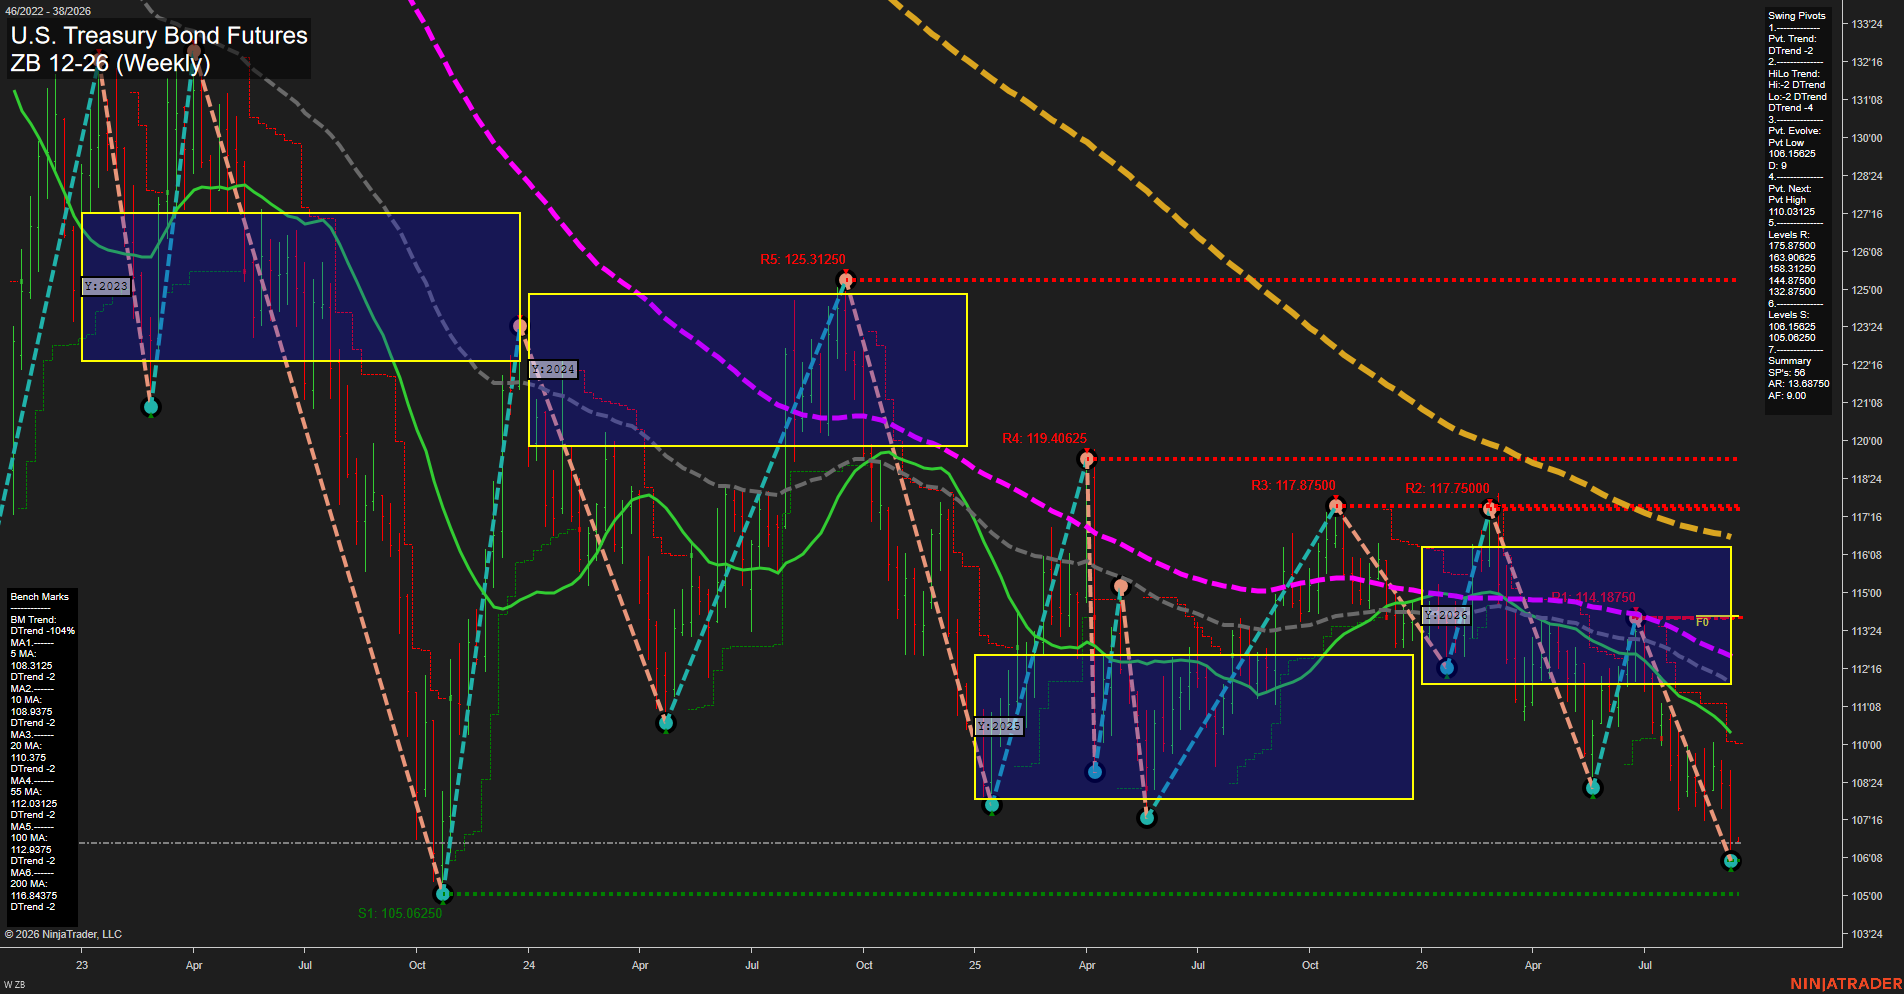
Overall Rating
- Short-Term: Bearish
- Intermediate-Term: Bearish
- Long-Term: Bearish.
Key Insights Summary
Price remains in a broad bearish swing structure, with lower pivot highs and lower pivot lows reinforced by all six declining weekly benchmarks. The current 106-08 area is testing the 106.15625 to 105.06250 support band following a persistent selloff; the small recent bars indicate slowing downside momentum rather than a confirmed reversal. A pivot-high evolution requires recovery through 110.03125, while the moving-average cluster from 108.3125 through 116.84375 defines substantial overhead trend resistance. Price is below the weekly, monthly, and yearly neutral zones, maintaining a bearish multi-timeframe technical condition.
View charts on: AlphaWebTrader HTF Charts