U.S. futures and global shares firm as oil supply fears ease and U.S.-China talks improve, while Treasury yields, Fed policy and geopolitics weigh.
Fundamentals: U.S. equity futures and global shares firm ahead of the Trump-Xi summit, supported by lower oil prices as Strait of Hormuz flows improve and officials describe U.S.-China discussions constructively. Technology and Chinese biopharma shares aid risk appetite, but elevated Treasury yields, the Fed's September rate hike, tanker constraints and Middle East tensions remain important market cross-currents.
Technicals: Pre-market conditions follow notable prior-session gains in IBIT, NVDA and AMZN, while META, USO and MSFT declined. S&P 500 and Nasdaq futures retain bullish short-, intermediate- and long-term technical ratings after V-shaped recoveries. Dow futures are mixed, while EMD, Russell 2000 and DAX contracts remain in corrective short-term structures despite constructive longer-term trends.
Pre-Market Trading 360° view Market Radar of: holidays, earnings, eco-news, market-news summary, news sentiment, prior session major ETFs, MAG7, Higher Time Frame Analysis Indices Futures Summary, and E-mini S&P500, Nasdaq 100, NYMEX Crude, Gold Futures Daily Chart analysis.
As of: September 21, 2026 07:16 CT
Market News Summary:
Index futures and global equities firm as easing oil-supply fears and constructive U.S.-China dialogue offset pressure from elevated Treasury yields and Fed tightening.
Primary Drivers & Risks:
- Primary Driver: Positive U.S.-China talks
- Primary Risk: Higher yields and Fed tightening
Tone:
Cautiously constructive, with rate and geopolitical cross-currents.
Stock Market / ETFs / Indices:
U.S. stock futures trend higher, while global stocks rally ahead of the Trump-Xi summit. Technology shares continue to support the S&P 500, Chinese biopharma stocks advance on potential continued U.S. drug-licensing access, and mid-cap valuations are described as attractive. Morgan Stanley highlights risk of a 7% S&P 500 decline despite the recent rebound.
Geopolitical:
U.S.-China officials describe weekend discussions on AI, trade and investment positively ahead of the leaders’ meeting. The United Nations gathering and Trump-Xi summit place Iran, trade, Ukraine and AI safety in focus. Diplomatic engagement with Iran is also cited as reducing immediate oil-market concern, despite continued regional tensions and attacks on Saudi Arabia.
Oil / Energy:
Oil falls for a fourth day as crude and LNG movements through the Strait of Hormuz improve and Saudi pipeline-disruption concerns ease. Tanker shortages and high Hormuz shipping rates remain a countervailing inflation pressure, with higher fuel costs already reported in Bangladesh.
Gold / Metals:
Gold and silver remain under pressure from elevated U.S. yields, central-bank rate increases and persistent inflation. Gold holds above noted support but faces selling pressure as tighter-policy expectations constrain recovery.
Fed / Financials:
Citi raises its year-end 10-year Treasury yield view to 5.0% following the Fed’s September rate hike. Bond markets remain weak despite large inflows into bond funds, while Société Générale raises its profitability target and expands cost-cutting plans.
Macro / Other:
AI-related power suppliers and equipment makers face multiple compression despite stronger earnings and guidance, underscoring valuation pressure in parts of the AI trade. AI access and safety remain central issues in U.S.-China discussions.
Conclusion:
Early equity strength is tied to lower crude prices, improved Hormuz flows and constructive U.S.-China dialogue. Technology leadership and selected China-sensitive sectors support the broader risk tone.
Elevated Treasury yields and Fed-tightening expectations remain a constraint on equities and metals. Middle East conflict, tanker capacity shortages and summit outcomes remain active cross-currents.
Market News Sentiment
Market News Articles: 22
- Neutral: 59.09%
- Negative: 22.73%
- Positive: 18.18%
Sentiment Summary: Market news sentiment is predominantly neutral at 59%, with negative coverage at 23% and positive coverage at 18%.
Conclusion: The news flow presents a neutral tone for indices futures day traders, with negative articles exceeding positive articles.
GLD,Gold Articles: 4
- Negative: 50.00%
- Positive: 25.00%
- Neutral: 25.00%
Sentiment Summary: GLD and gold coverage is mixed-to-negative, with 50% negative, 25% positive, and 25% neutral articles.
Conclusion: Gold-related news tone is predominantly negative, which may be relevant as a cross-market sentiment input for indices futures day traders.
USO,Oil Articles: 7
- Negative: 71.43%
- Positive: 14.29%
- Neutral: 14.29%
Sentiment Summary: USO/Oil coverage is predominantly negative, with 71% negative, 14% positive, and 14% neutral articles.
Conclusion: Oil-related news tone is negative, which may be relevant context for energy-sensitive index futures.
Market Data Snapshot
ETF Snapshot of major stock market ETFs, Mag7, and others as of: September 21, 2026 07:16
Top Movers & Losers
- IBIT 46.02 Bullish 6.28% ▲
- NVDA 222.27 Bullish 1.34% ▲
- AMZN 253.71 Bullish 1.00% ▲
- MSFT 493.78 Bearish -0.80% ▼
- USO 153.82 Bearish -0.96% ▼
- META 665.75 Bearish -2.43% ▼
Major Index ETFs: SPY, QQQ, DIA, IWM, IJH
- QQQ 721.45 Bullish 0.63% ▲
- SPY 761.69 Bearish -0.12% ▼
- IJH 72.98 Bearish -0.31% ▼
- IWM 284.10 Bearish -0.47% ▼
- DIA 515.88 Bearish -0.48% ▼
Mixed: QQQ is the most bullish mover at +0.63%, while DIA is the most bearish mover at -0.48%. SPY is marginally Bearish at -0.12%, with IJH at -0.31% and IWM at -0.47%.
Mag 7 Stocks: AAPL, MSFT, GOOG, AMZN, META, NVDA, TSLA
- NVDA 222.27 Bullish 1.34% ▲
- AMZN 253.71 Bullish 1.00% ▲
- GOOG 344.41 Bullish 0.21% ▲
- AAPL 336.13 Bearish -0.26% ▼
- TSLA 364.27 Bearish -0.53% ▼
- MSFT 493.78 Bearish -0.80% ▼
- META 665.75 Bearish -2.43% ▼
Mixed: NVDA is the most bullish mover at +1.34%, followed by AMZN at +1.00%; GOOG is marginally Bullish at +0.21%. META is the most bearish mover at -2.43%, with MSFT at -0.80%, TSLA at -0.53%, and AAPL near-flat Bearish at -0.26%.
Cross-Market ETFs: TLT, GLD, USO, IBIT
- IBIT 46.02 Bullish 6.28% ▲
- GLD 401.17 Bullish 0.71% ▲
- TLT 81.25 Bearish -0.65% ▼
- USO 153.82 Bearish -0.96% ▼
Mixed cross-market snapshot: IBIT is the most bullish mover at +6.28%, while USO is the most bearish mover at -0.96%. GLD is Bullish at +0.71%, while TLT is Bearish at -0.65%.
ETF, Mag7, and Cross-Market ETF Insights
Overall Tone
Mixed: strong IBIT and selective technology gains contrast with broadly Bearish equity breadth, softer bonds, and weaker oil.
Equity ETFs and Mag7:
Major Index ETFs were Mixed: QQQ gained +0.63%, while SPY was marginally Bearish at -0.12% and DIA, IWM, and IJH declined -0.48%, -0.47%, and -0.31%, respectively. Mag7 performance was selective, led by NVDA at +1.34%, followed by AMZN at +1.00% and GOOG at +0.21%; META was the most bearish mover at -2.43%, with MSFT -0.80%, TSLA -0.53%, and AAPL -0.26% also Bearish. Equity leadership was concentrated rather than broadly aligned.
Cross-Market ETFs:
Cross-market ETFs were Mixed, with IBIT the most bullish mover at +6.28% and GLD also Bullish at +0.71%. TLT fell -0.65%, while USO was the most bearish cross-market mover at -0.96%, showing divergence from the strength in IBIT and GLD.
Futures Indices – Higher Time Frame Analysis
Summary of the current state of US Indices Futures based on higher time-frame (HTF) technical analysis as of: 2026-09-21: 07:16 CT.
US Indices Futures
- ES YSFG/MSFG/WSFG above F0%, benchmarks rising, UTrend pivots, 7906.25 resistance, 7559.25 support, 7655.25–7755.75 benchmark zone.
- NQ YSFG/MSFG/WSFG above F0%, above rising benchmarks, UTrend pivots, 30842.25/31389.25 resistance, 29879.50–28803.25 support references.
- YM YSFG/WSFG above F0%, MSFG below F0%, short benchmarks declining, DTrend pivots, 52747/53953 resistance, 51609 support.
- EMD YSFG above F0%, MSFG below F0%, below short benchmarks, bearish pivots, 3833.8 reversal resistance, 3636.2 support, 200-day near 3674.5.
- RTY YSFG/WSFG above F0%, MSFG below F0%, below declining short benchmarks, DTrend pivots, 2927.1/3005.2 resistance, 2850 support.
- FDAX YSFG above F0%, MSFG below F0%, near weekly 20-period benchmark, corrective DTrend, 25990/26728–26847 resistance, 25362 support.
Overall State
- Short-Term: Bearish
- Intermediate-Term: Bearish
- Long-Term: Bullish
Conclusion
ES and NQ retain aligned bullish HTF structures, with Fib grids above F0%, rising benchmarks, and upward pivots. YM is mixed, while EMD and RTY retain bearish short-to-intermediate structures. FDAX is rebounding from support within an intermediate corrective sequence. Across YM, EMD, RTY, and FDAX, YSFG positioning and rising long-term benchmarks maintain broader bullish context, while MSFG weakness, declining short benchmarks, and lower pivot structures define current retracement phases.
Note: Intra-day counter-trend pullbacks or retracements may occur, HTF is context for informational usage and market structure. Glossary: Session Fib Grids periods of YSFG:’Yearly’, MSFG:’Monthly’, WSFG:’Weekly’
For full details visit: AlphaWebTrader Technicals
ES Daily View
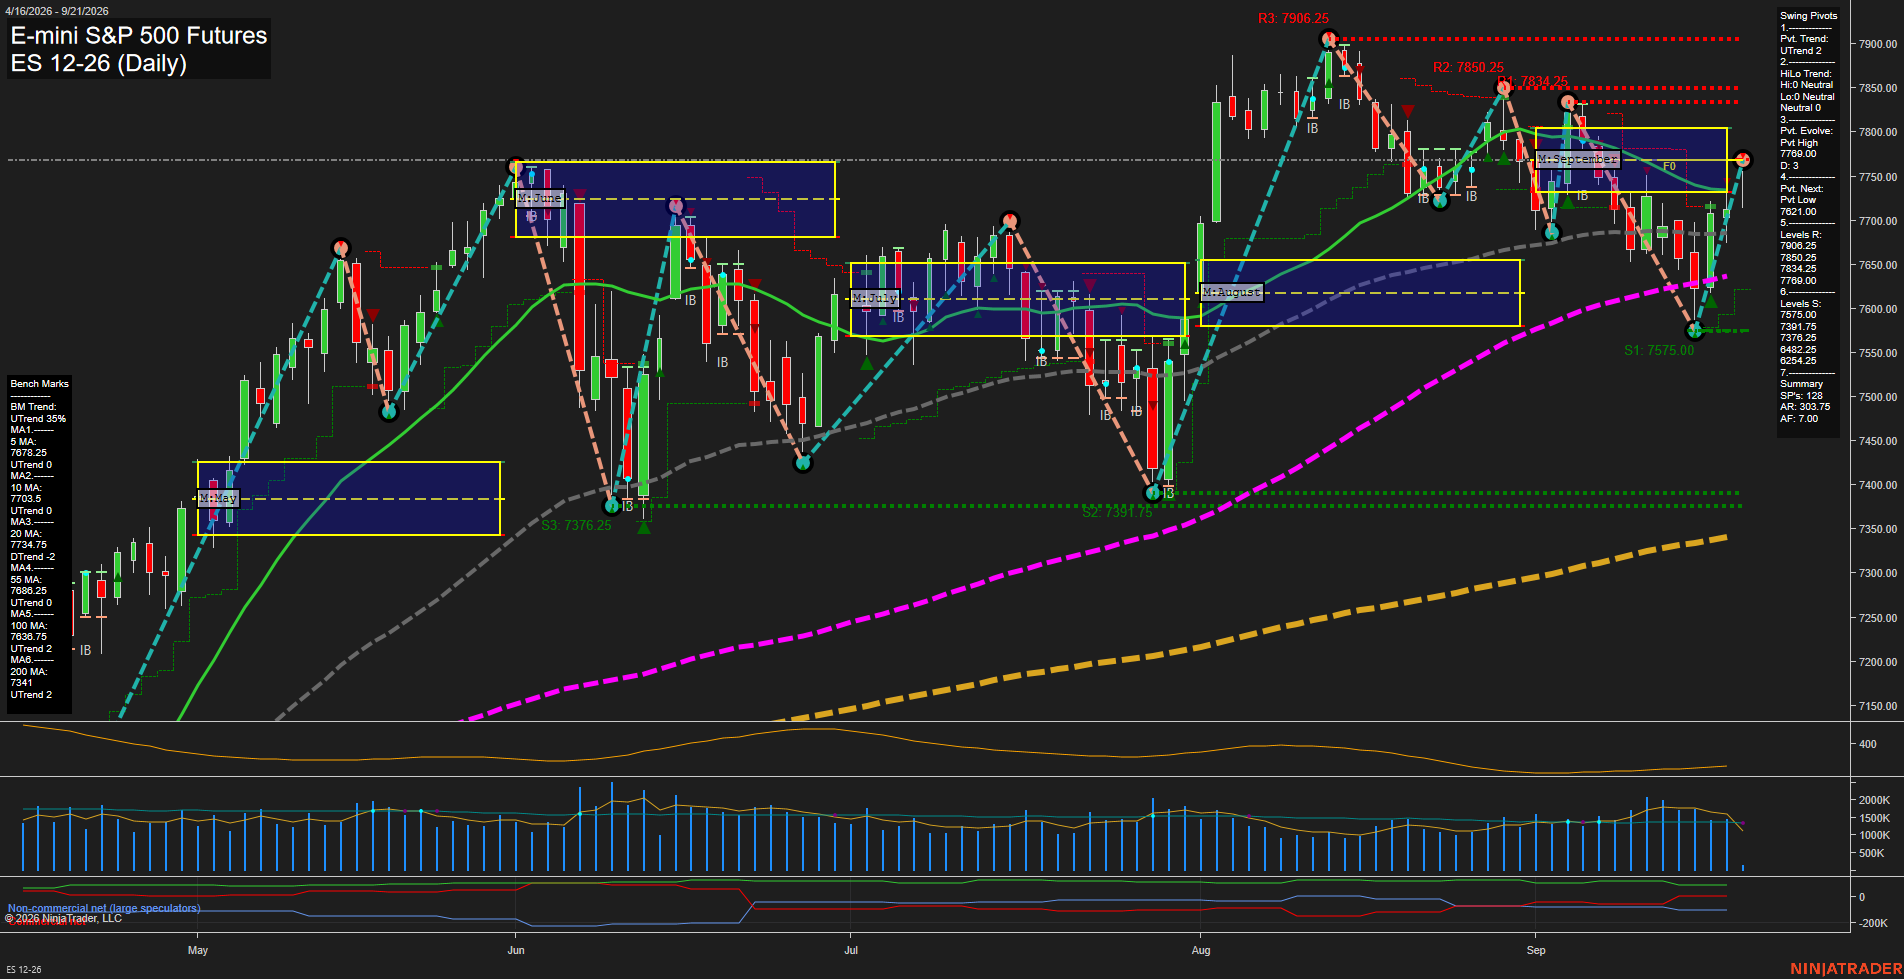
Overall Rating
- Short-Term: Bullish
- Intermediate-Term: Bullish
- Long-Term: Bullish.
Key Insights Summary
The daily structure has regained upside momentum through a large recovery bar, with price above the weekly and monthly F0% areas and above all major benchmarks except the declining 20-day average. The short-term pivot trend is upward and price is pressing the 7780.00 resistance area after a sharp rebound from the 7391.75 pivot-support zone. Intermediate and long-term structure remains constructive through rising 55-, 100-, and 200-day averages, while the 20-day average reflects the recent corrective swing. The immediate pattern is a V-shaped recovery within a broader uptrend, with 7780.00, 7834.25, and 7850.25 defining the nearby overhead pivot-resistance sequence.
View charts on: AlphaWebTrader HTF Charts
NQ Daily View
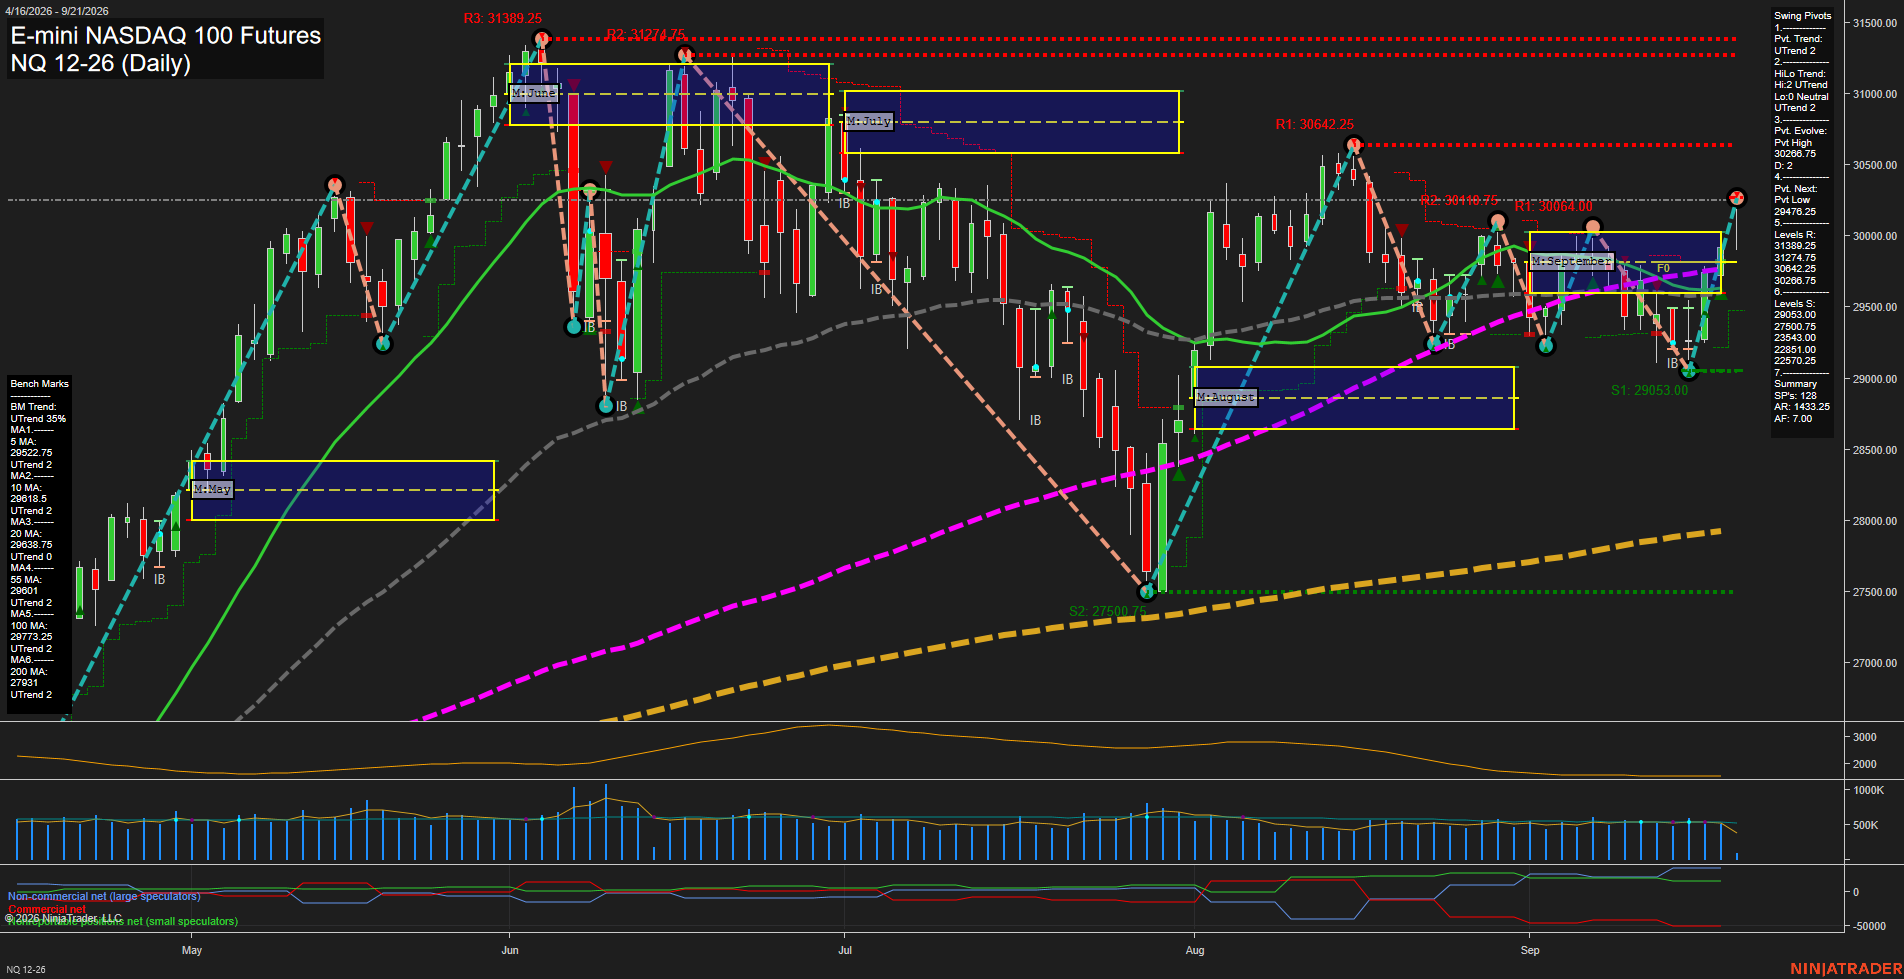
Overall Rating
- Short-Term: Bullish
- Intermediate-Term: Bullish
- Long-Term: Bullish.
Key Insights Summary
The daily structure reflects a strong V-recovery continuation: price has surged from the 29053.00 swing-support area, reclaimed every displayed benchmark average, and established a new short-term pivot high at 30266.75. Weekly, monthly, and yearly Fib-grid positioning remains above F0%, aligning the short-, intermediate-, and long-term trend themes. Fast momentum and large daily bars indicate an expansion phase rather than a quiet consolidation, with 30064.00 through 30642.25 defining the nearest overhead pivot-resistance band. The 29476.25 pivot-next level and 29053.00 support are the principal nearby structural references beneath the advance.
View charts on: AlphaWebTrader HTF Charts
CL Daily View
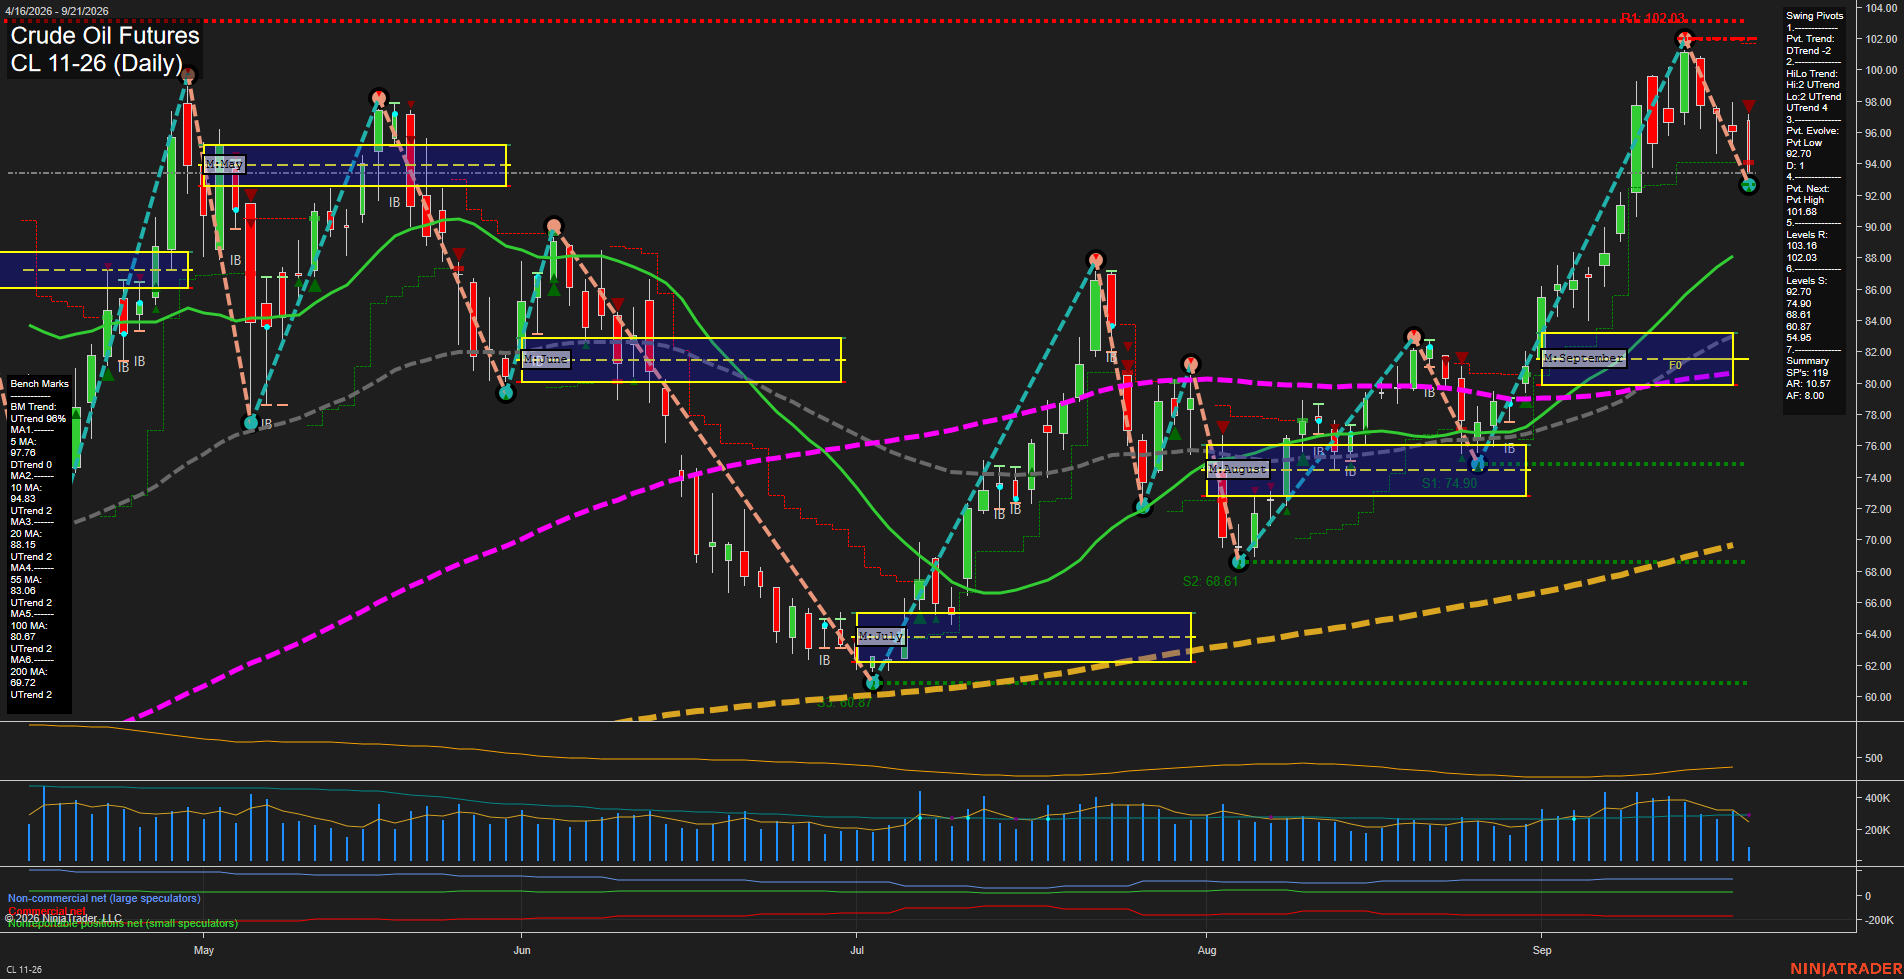
Overall Rating
- Short-Term: Bearish
- Intermediate-Term: Bullish
- Long-Term: Bullish.
Key Insights Summary
Price has undergone a fast, large-bar retracement from the 102.03 pivot resistance area, shifting the short-term pivot structure into DTrend and placing price below the weekly F0% grid. The 5-day benchmark is declining and price is below the 10-day average, confirming near-term downside momentum. The broader structure remains constructive: price holds above the rising 20-, 55-, 100-, and 200-day benchmarks, the monthly grid remains positive, and the intermediate HiLo pivot trend is still UTrend. The 92.70 pivot low is the immediate short-term structural level, while 101.68 to 102.03 defines the overhead swing-high resistance zone.
View charts on: AlphaWebTrader HTF Charts
GC Daily View
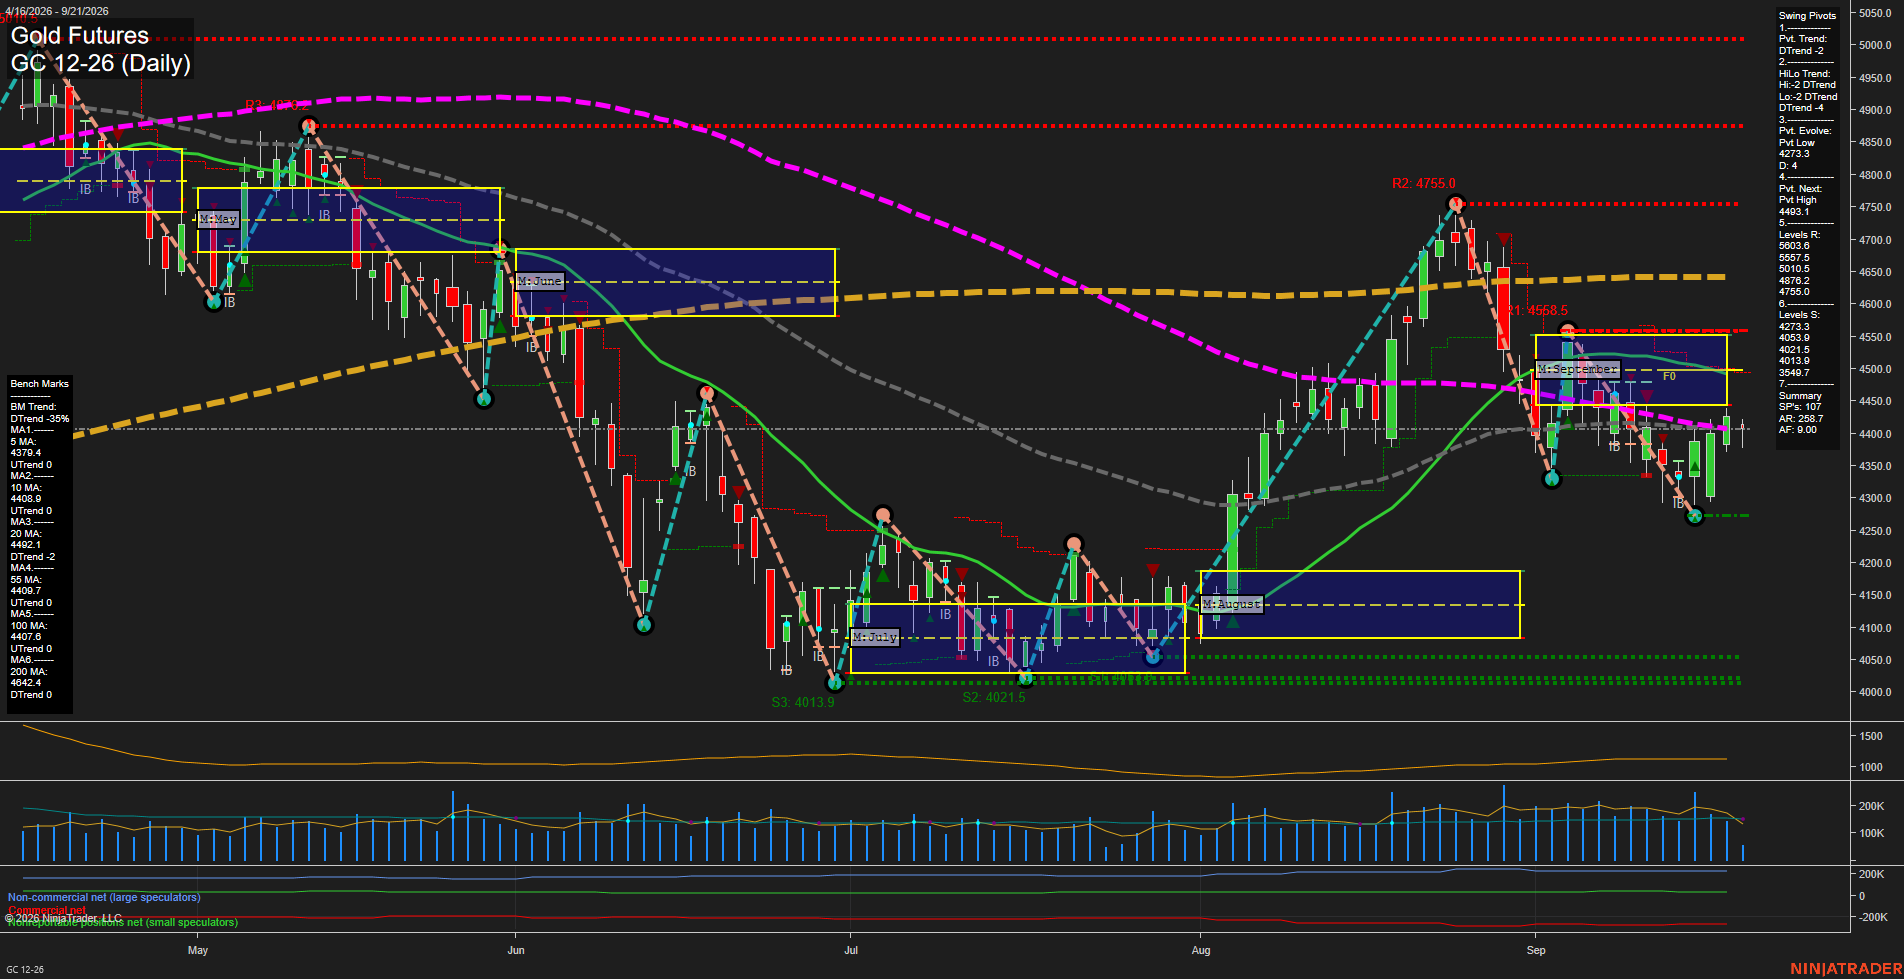
Overall Rating
- Short-Term: Bearish
- Intermediate-Term: Bearish
- Long-Term: Bearish.
Key Insights Summary
Price is rebounding from the 4271.3 pivot low, but the broader swing structure remains downward with both Pivot Trend and HiLo Trend in DTrend. The recovery has lifted price marginally above the 5-day, 10-day, 55-day, and 100-day benchmarks, while the declining 20-day average at 4442.9 and the 4493.1 pivot-reversal threshold define the nearby overhead test zone. Weekly, monthly, and yearly fib-grid readings remain below F0%, reflecting a bearish multi-timeframe backdrop. The recent action is a volatile counter-trend bounce within a larger decline, with 4273.3 as primary nearby support and 4755.0 as major visible swing resistance.
View charts on: AlphaWebTrader HTF Charts
ZB Daily View
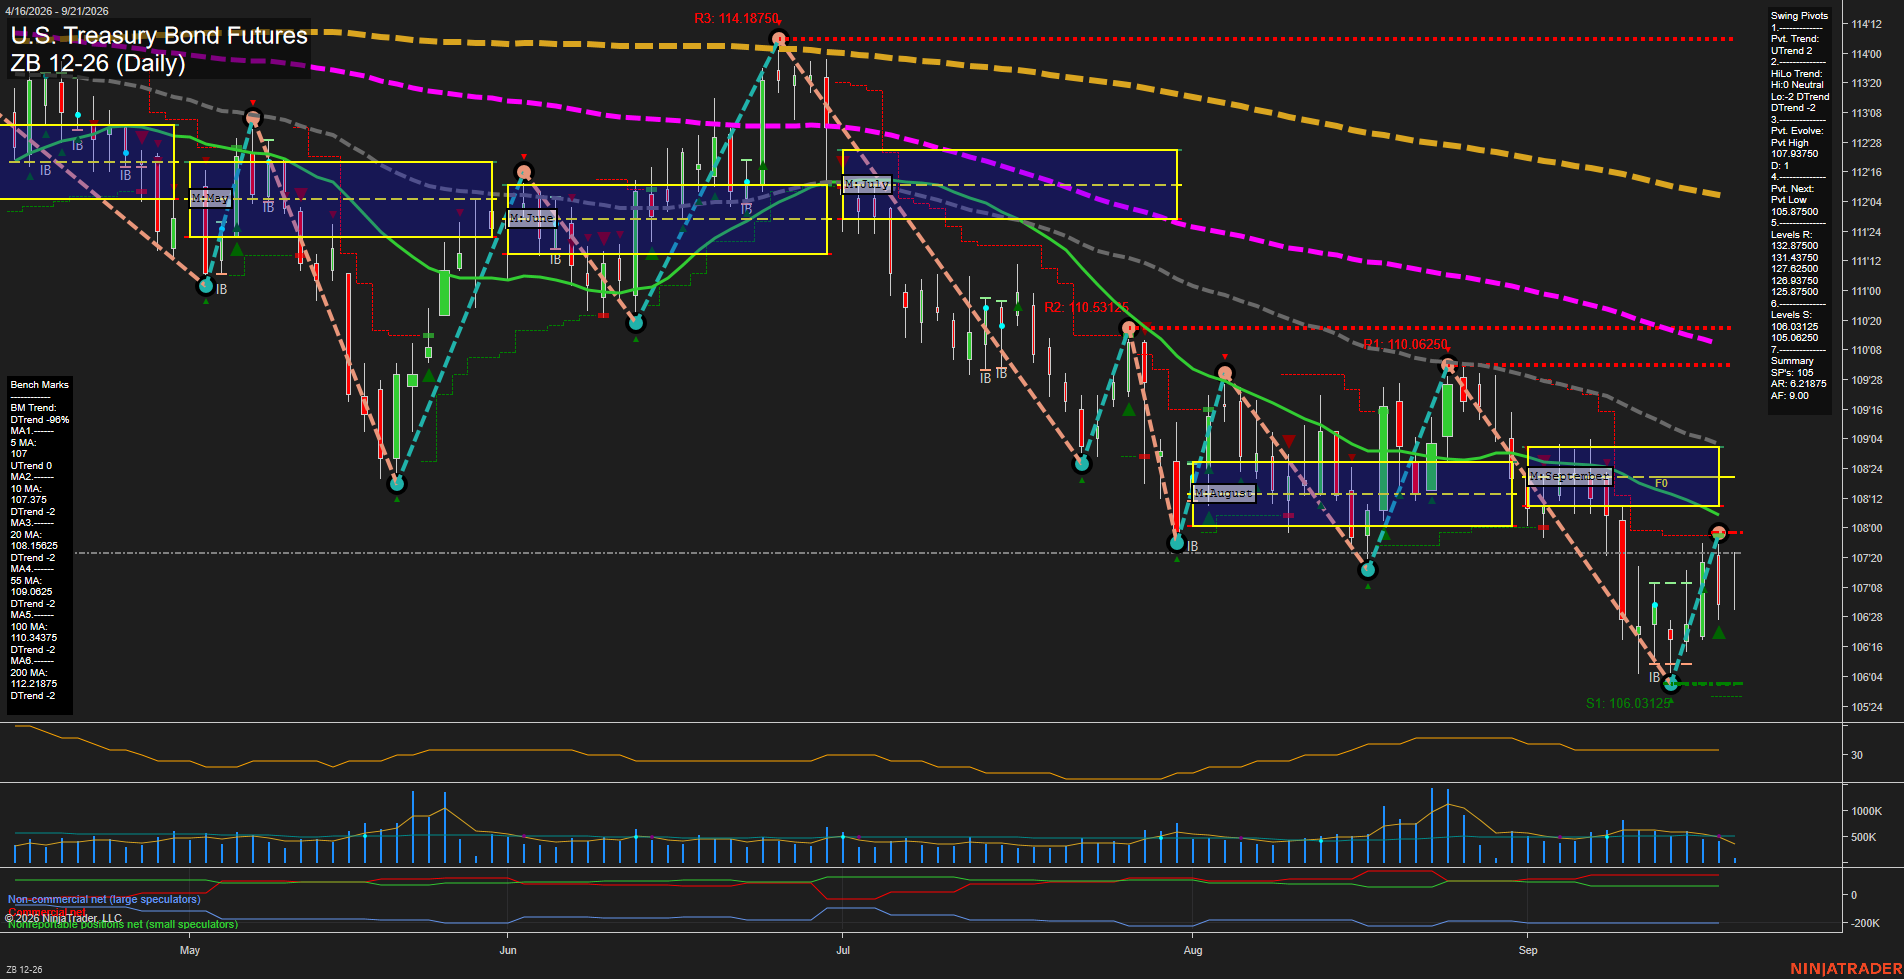
Overall Rating
- Short-Term: Neutral
- Intermediate-Term: Bearish
- Long-Term: Bearish.
Key Insights Summary
Price is staging a fast short-term rebound from the 106.03125 swing-low area and has established a current UTrend pivot sequence, but the rally is testing into nearby resistance around 107.87500-108.00000 while remaining below the September NTZ and the declining 10-, 20-, 55-, 100-, and 200-day benchmarks. The intermediate and long-term structure remains a lower-high/downtrend environment. The recent recovery resembles a counter-trend bounce inside the broader decline, with 106.03125 and 105.06250 defining the principal downside swing-support references.
View charts on: AlphaWebTrader HTF Charts